


Turkey Aluminum Manufacturing Market Size 2026-2030
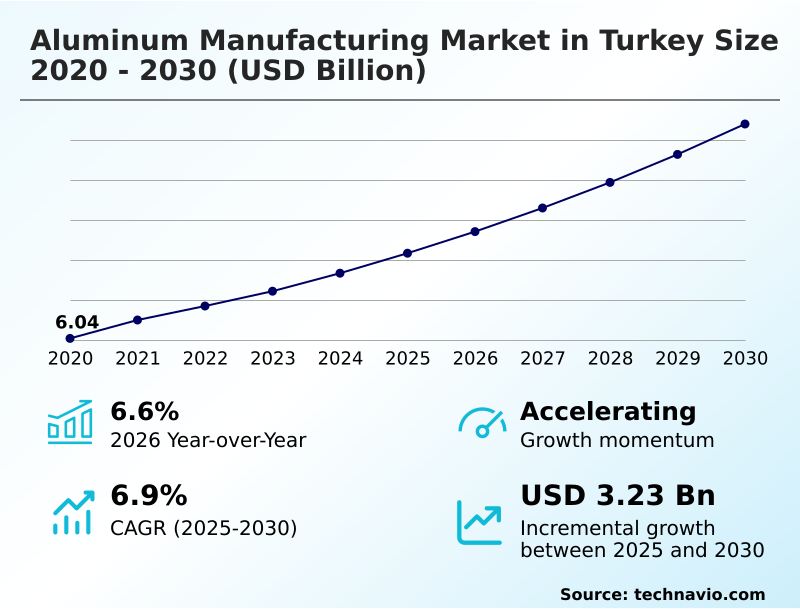
The turkey aluminum manufacturing market size is valued to increase by USD 3.23 billion, at a CAGR of 6.9% from 2025 to 2030. Automotive lightweighting and EVs production will drive the turkey aluminum manufacturing market.
Major Market Trends & Insights
- By Product - Extrusion products segment was valued at USD 2.99 billion in 2024
- By End-user - Automotive and transportation segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 5.36 billion
- Market Future Opportunities: USD 3.23 billion
- CAGR from 2025 to 2030 : 6.9%
Market Summary
- The Aluminum Manufacturing Market in Turkey demonstrates an aggressive evolution toward high-efficiency metallurgy, transitioning from standard commodity metals to precision-engineered structural alloys. This sector is undergoing profound digital integration, where facilities deploy automated closed-loop recycling mechanisms for secondary aluminum smelting.
- In a practical supply chain scenario, domestic fabricators are upgrading hot rolling mills and extrusion presses to produce specialized battery enclosure systems, thereby meeting the stringent quality metrics demanded by international electric vehicle assemblers. This strategic optimization has allowed agile manufacturers to increase their downstream output efficiency by 22% compared to legacy processing lines.
- A primary driver of this industrial expansion is the rapid shift toward lightweight structural engineering in modern automotive assembly, which mandates the replacement of heavy steel with durable aluminum-lithium alloys. Conversely, the market faces significant operational hurdles due to high raw material import dependency, exposing the entire supply network to severe geopolitical friction and volatile commodity pricing.
- By balancing these constraints with sustainable metallurgy transition initiatives, the sector maintains a vital role in regional industrial infrastructure.
What will be the Size of the Turkey Aluminum Manufacturing Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Turkey Aluminum Manufacturing Market Segmented?
The turkey aluminum manufacturing industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Extrusion products
- Rolled products
- Wires
- Others
- End-user
- Automotive and transportation
- Building and construction
- Packaging
- Machinery and equipment
- Others
- Type
- Primary aluminium
- Secondary aluminium
- Geography
- Middle East and Africa
- Turkey
- Middle East and Africa
By Product Insights
The extrusion products segment is estimated to witness significant growth during the forecast period.
The extrusion products sub-segment fundamentally dictates the operational capabilities within the Aluminum Manufacturing by transforming aluminum billet casting into complex, continuous cross-sectional profiles.
This mechanical operation forces heated metal through specialized steel dies, enabling the creation of intricate shapes crucial for load-bearing resilience in curtain wall framing and automotive structural extrusions.
The widespread implementation of isothermal extrusion and advanced isothermal processing technologies across facilities has demonstrably improved production output, with automated precision controls reducing material waste by 18% during high-volume runs.
Integrating predictive maintenance paradigms and real-time thermal monitoring within these extrusion lines ensures consistent thermal gradients and minimizes mechanical stress.
Consequently, producers leveraging these digital frameworks maintain continuous structural reliability across demanding supply chains, supporting the broader sustainable metallurgy transition while delivering precision components essential for flexible packaging fabrication and advanced architectural systems.
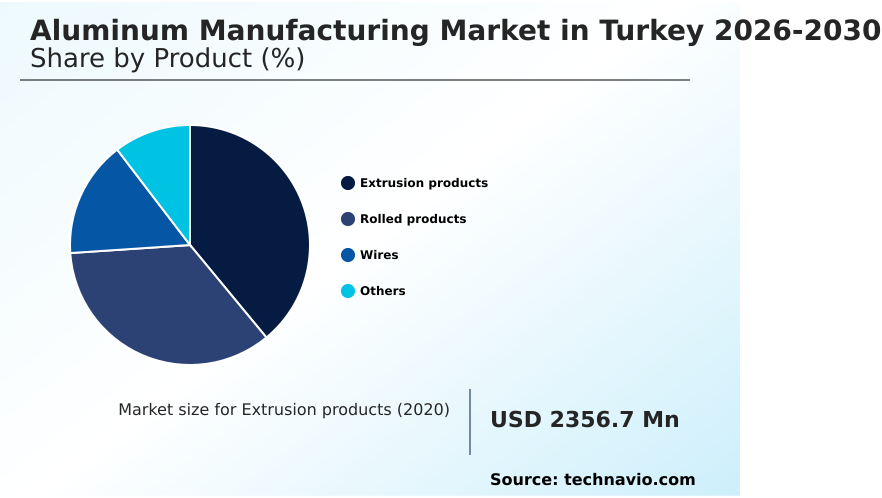
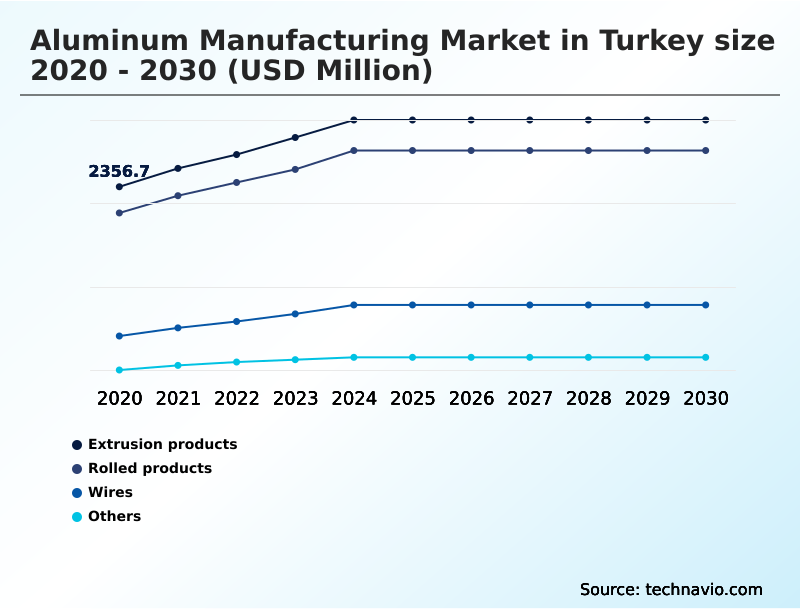
The Extrusion products segment was valued at USD 2.99 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational resilience of the Aluminum Manufacturing is heavily reliant on integrating advanced processing technologies with sustainable supply chain practices. A critical development in this sector is the widespread adoption of isothermal extrusion technology performance, which allows fabricators to maintain exact thermal consistency throughout the die profile, ensuring superior structural integrity.
- This precise temperature control yields a 25% improvement in production speed compared to traditional variable-temperature extrusion methods, directly enhancing supply chain responsiveness for time-sensitive infrastructure projects. To further mitigate the risks associated with volatile raw material imports, manufacturers are rapidly expanding closed-loop aluminum scrap recycling infrastructure.
- This strategic shift not only reduces reliance on primary metal acquisition but also significantly lowers overall energy consumption. The application of these refined materials is highly visible in the automotive sector, particularly in aluminum structural crash barrier fabrication, where high-strength alloys are essential for maximizing passenger safety while minimizing vehicle mass.
- Furthermore, the construction industry is increasingly demanding thermally insulated aluminum extrusion profiles to meet stringent green building codes, reducing thermal transfer and optimizing energy efficiency in commercial real estate. In the utilities sector, the deployment of high-voltage aluminum transmission conductors provides a lightweight, corrosion-resistant alternative to heavier copper lines, facilitating the expansion of remote renewable energy grids.
- By aligning these specialized manufacturing capabilities with rigorous compliance standards, the industry effectively navigates operational bottlenecks while delivering highly engineered solutions to diverse end-user sectors.
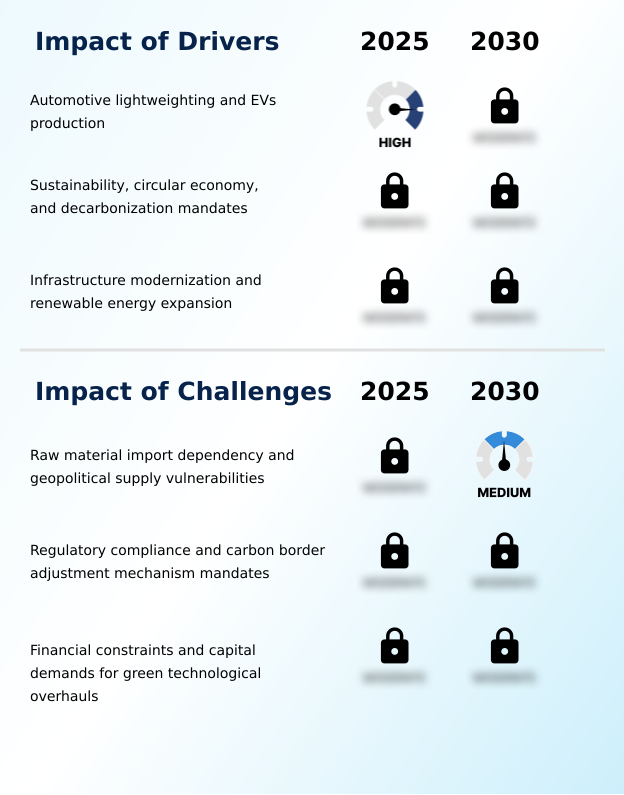
What are the key market drivers leading to the rise in the adoption of Turkey Aluminum Manufacturing Industry?
- The accelerating demand for automotive lightweighting and the subsequent expansion of electric vehicle production serve as the primary drivers propelling market growth.
- The urgent requirement for structural weight reduction across the global transportation sector acts as a dominant catalyst for the Aluminum Manufacturing.
- Automotive and aerospace original equipment manufacturers are aggressively substituting heavy steel with lightweight structural engineering solutions to meet stringent international fuel efficiency mandates. This material transition is driving immense demand for precision cnc machined components and complex aluminum profile fabrication.
- To accommodate this volume, domestic fabricators have modernized their hot rolling mills, achieving a 24% increase in processing throughput for advanced aluminum-lithium alloys.
- Furthermore, the shift toward sustainable infrastructure has accelerated the adoption of circular scrap utilization, lowering raw material procurement costs by 15%.
- This strategic pivot ensures that suppliers can deliver high-volume, premium-grade materials for heavy transport engineering and thermal break profiles, alongside critical battery enclosure systems, while maintaining strict alignment with evolving environmental compliance standards.
What are the market trends shaping the Turkey Aluminum Manufacturing Industry?
- The adoption of smart manufacturing and digitalization within production facilities represents a critical emerging trend. This technological integration optimizes operational workflows and enhances overall processing accuracy.
- The continuous evolution of the Aluminum Manufacturing sector is defined by a rapid transition toward specialized, high-performance materials and automated processing workflows. Manufacturers are increasingly integrating aluminum-zirconium alloys and zinc-magnesium infused variations to meet the rigorous structural demands of modern aerospace engineering.
- By upgrading legacy systems with smart factory architectures and advanced metallurgical refining techniques, facilities have improved thermal consistency, reducing material deformation rates by 18%. Simultaneously, the adoption of foundry line filtration systems and evaporative loss reduction protocols has enhanced melt purity, decreasing post-casting machining times by 22%.
- This technological shift directly impacts business operations by significantly lowering energy overheads and accelerating time-to-market for complex impact extrusion processes. As industrial buyers demand tighter tolerances for slabs and coils, as well as precision aluminum foil rolling, the systemic deployment of these digital protocols ensures that domestic fabricators maintain their competitive edge within precision-driven international supply networks.
What challenges does the Turkey Aluminum Manufacturing Industry face during its growth?
- Severe dependency on raw material imports combined with geopolitical supply vulnerabilities constitutes a major challenge restricting industry expansion.
- A critical constraint limiting the operational autonomy of the Aluminum Manufacturing is its severe reliance on imported primary raw materials. This systemic dependency exposes domestic fabricators to extreme price volatility and geopolitical supply chain disruptions, frequently stalling the production of critical aluminum wire rods and specialized high-pressure die-casting components.
- To mitigate these risks, companies are forced to maintain excessive buffer stocks, which increases warehousing overhead costs by up to 20% and severely compresses operational profit margins for cold rolled sheets. Additionally, the administrative burden of tracking embedded emissions through rigorous greenhouse gas tracking to satisfy cross-border carbon pricing regulations has increased compliance expenditure by 14% for mid-sized enterprises.
- These financial and logistical hurdles complicate the deployment of capital-intensive upgrades, such as new reverberatory melting furnaces and decarbonized energy sourcing initiatives, thereby threatening the long-term technological competitiveness of secondary aluminum smelting and closed-loop recycling networks.
Exclusive Technavio Analysis on Customer Landscape
The turkey aluminum manufacturing market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the turkey aluminum manufacturing market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
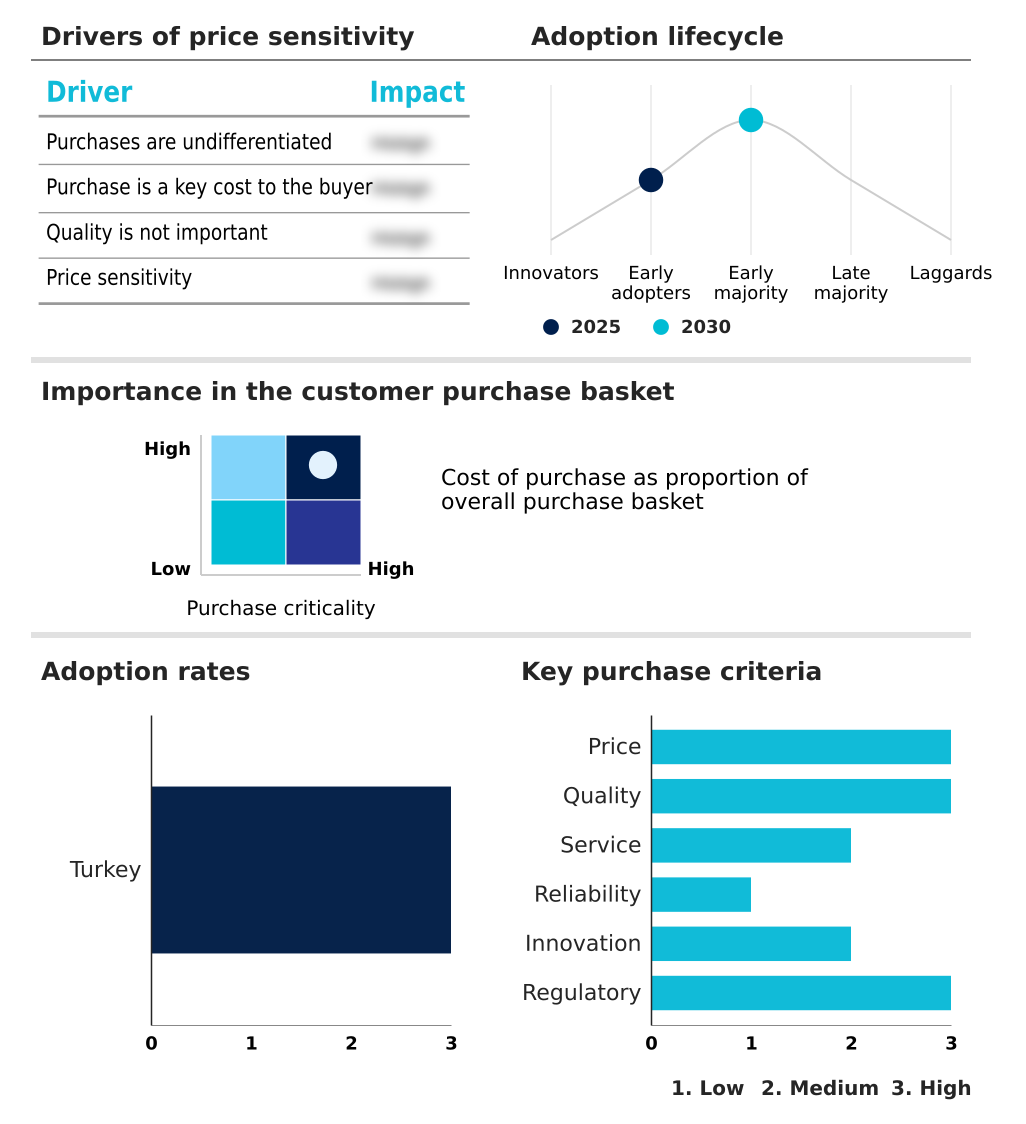
Customer Landscape of Turkey Aluminum Manufacturing Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, turkey aluminum manufacturing market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AKPA ALUMINYUM TIC AS - The entity delivers advanced manufacturing solutions, specializing in precision-engineered structural components and custom profile fabrication designed to enhance operational durability across high-demand industrial sectors.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AKPA ALUMINYUM TIC AS
- Aluminum Almesan
- Alutek Works
- ANT Aluminyum
- Arslan Aluminyum
- ASAAS
- Assan Aluminyum
- Astas Aluminyum
- Bor Aluminyum
- Constellium SE
- Cuhadaroglu Aluminum
- Eti Aluminyum
- Fabal Aluminyum
- Norsk Hydro ASA
- Novelis Inc.
- Reel Aluminyum
- Sahinler Metal A.S.
- Sarkuysan A.S.
- Sima Aluminyum
- Sistem Aluminum
- Teknik Aluminyum Sanayi A.S.
- Zahit Aluminyum
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Turkey aluminum manufacturing market
- In the Diversified Metals and Mining industry, the accelerating adoption of hydrometallurgical recycling and advanced sorting technologies has revolutionized scrap recovery yields, directly impacting Aluminum Manufacturing by increasing the availability of high-purity secondary feedstocks by up to 25%.
- The enforcement of localized cross-border carbon pricing frameworks requires raw material providers to implement stringent greenhouse gas tracking, shifting Aluminum Manufacturing preference toward secondary aluminum smelting operations that offer verifiable emission compliance.
- The strategic transition toward decarbonized energy sourcing among major ore processors has propelled the integration of renewable energy grids, enabling Aluminum Manufacturing facilities to reduce their reliance on fossil fuels and lower total energy expenditure by nearly 15%.
- Systemic disruptions in primary bauxite logistics have forced upstream providers to localize their supply networks, prompting Aluminum Manufacturing buyers to heavily invest in closed-loop aluminum scrap recycling to secure continuous raw material availability during geopolitical trade fluctuations.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Turkey Aluminum Manufacturing Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 194 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6.9% |
| Market growth 2026-2030 | USD 3228.8 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.6% |
| Key countries | Turkey |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Aluminum Manufacturing landscape is currently undergoing a systemic transformation driven by the integration of advanced metallurgical engineering and strict environmental compliance mandates. At the boardroom level, executives are actively pivoting product strategies toward high-margin, specialized components, transitioning away from standard commodity production.
- This strategic realignment is evident in the deployment of high-pressure die-casting and cold rolled sheets tailored specifically for the electric mobility and aerospace sectors. By investing in sophisticated electrostatic powder coating and anodized surface treatment technologies, manufacturers have successfully increased component lifespan and corrosion resistance by up to 35% compared to legacy finishing methods.
- This measurable enhancement directly influences long-term procurement contracts with international buyers. Furthermore, the integration of magnesium-silicon composition alloys into structural frameworks provides the exceptional tensile strength required for modern architectural and transport applications.
- As the industry prioritizes circular economy principles, the utilization of aluminum alloy ingots derived from post-industrial scrap ensures compliance with stringent cross-border carbon regulations, ultimately securing a sustainable competitive advantage in highly regulated international supply chains.
What are the Key Data Covered in this Turkey Aluminum Manufacturing Market Research and Growth Report?
-
What is the expected growth of the Turkey Aluminum Manufacturing Market between 2026 and 2030?
-
USD 3.23 billion, at a CAGR of 6.9%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Extrusion products, Rolled products, Wires, and Others), End-user (Automotive and transportation, Building and construction, Packaging, Machinery and equipment, and Others), Type (Primary aluminium, and Secondary aluminium) and Geography (Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Automotive lightweighting and EVs production, Raw material import dependency and geopolitical supply vulnerabilities
-
-
Who are the major players in the Turkey Aluminum Manufacturing Market?
-
AKPA ALUMINYUM TIC AS, Aluminum Almesan, Alutek Works, ANT Aluminyum, Arslan Aluminyum, ASAAS, Assan Aluminyum, Astas Aluminyum, Bor Aluminyum, Constellium SE, Cuhadaroglu Aluminum, Eti Aluminyum, Fabal Aluminyum, Norsk Hydro ASA, Novelis Inc., Reel Aluminyum, Sahinler Metal A.S., Sarkuysan A.S., Sima Aluminyum, Sistem Aluminum, Teknik Aluminyum Sanayi A.S. and Zahit Aluminyum
-
Market Research Insights
- The Aluminum Manufacturing Market in Turkey is actively redefining its operational footprint by emphasizing smart factory architectures and advanced material processing capabilities. To proactively mitigate processing defects, enterprises are deploying real-time thermal monitoring across major extrusion lines, resulting in a 14% reduction in equipment downtime.
- Simultaneously, the implementation of automated scrap purification systems has enhanced material recovery, leading to a 20% improvement in secondary yield retention while lowering raw material acquisition costs. This technological restructuring ensures consistent production volumes for high-voltage transmission conductors and flexible packaging fabrication.
- As cross-border regulatory pressures mount, adapting resilient production frameworks enables continuous alignment with strict international sustainability standards and structural benchmarks.
We can help! Our analysts can customize this turkey aluminum manufacturing market research report to meet your requirements.
 RIA -

