Fresh Meat Packaging Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), and Rest of World (ROW)

Fresh Meat Packaging Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), and Rest of World (ROW)

Published: Nov 2026 312 Pages SKU: IRTNTR44156

Market Overview at a Glance

$593.8 Mn
Market Opportunity
3.7%
CAGR 2025 - 2030
35.1%
North America Growth
$2.04 B
Flexible segment 2024

Fresh Meat Packaging Market Size 2026-2030

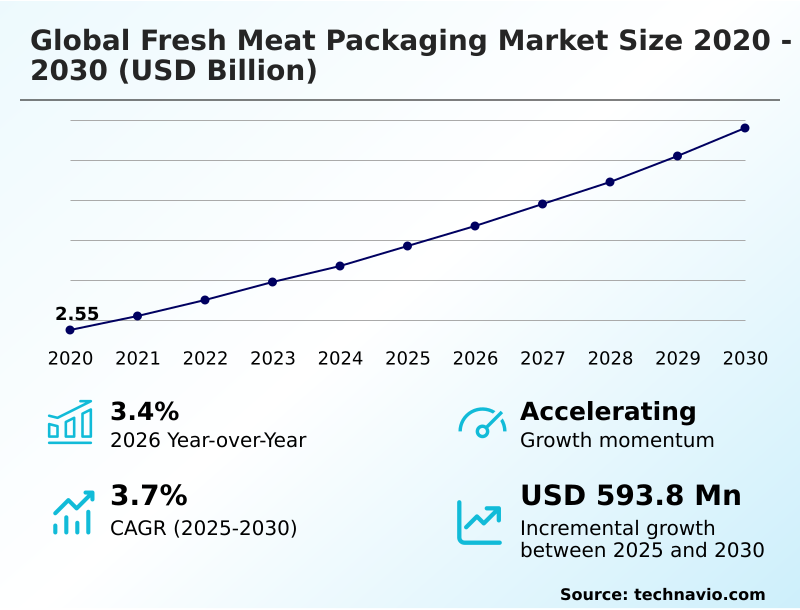
The fresh meat packaging market size is valued to increase by USD 593.8 million, at a CAGR of 3.7% from 2025 to 2030. Growing demand for extended shelf-life solutions in fresh meat distribution will drive the fresh meat packaging market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 35.1% growth during the forecast period.
  • By Packaging - Flexible segment was valued at USD 2.04 billion in 2024
  • By Type - Beef segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.01 billion
  • Market Future Opportunities: USD 593.8 million
  • CAGR from 2025 to 2030 : 3.7%

Market Summary

  • The Fresh Meat Packaging exhibits steady expansion driven by the critical necessity to maintain cold chain integrity and optimize visual merchandising appeal. Operations within the meat processing sector increasingly rely on high-speed traysealers and modified atmosphere packaging to fulfill the demands of organized retail distribution.
  • For example, optimizing tray-sealing automation alongside gas-flushing technologies has enabled processors to cut product spoilage rates by 15%, directly enhancing overall supply chain efficiency. A major driver propelling this sector is the growing demand for extended shelf-life extension systems; as retailers manage geographically dispersed networks, utilizing advanced oxygen transmission rate control helps extend freshness and reduce operational waste.
  • Conversely, the market faces significant challenges stemming from volatility in polymer resin procurement. Unpredictable raw material pricing compresses manufacturing margins, complicating long-term capacity planning for producers of bio-based compostable films and corrugated leakproof boxes. To navigate these constraints, organizations are aggressively pursuing circular packaging objectives to stabilize input costs and align with stringent post-consumer material recovery mandates.

What will be the Size of the Fresh Meat Packaging Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Fresh Meat Packaging Market Segmented?

The fresh meat packaging industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Packaging
    • Flexible
    • Rigid
  • Type
    • Beef
    • Pork
    • Goat meat/mutton
    • Poultry
    • Seafood
  • Material
    • Plastic
    • Paper and paperboard
    • Metal
    • Biodegradable
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • South Africa
      • UAE
      • Turkey
      • Israel

By Packaging Insights

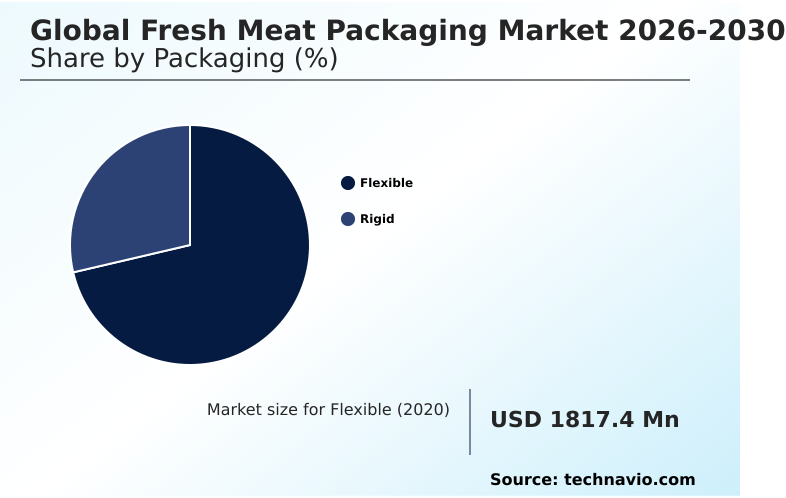
The flexible segment is estimated to witness significant growth during the forecast period.

The flexible segment of the Fresh Meat Packaging demonstrates continuous evolution, driven by the necessity for advanced packaging formats. Utilizing high-barrier multilayer films and flexible vacuum pouches, this segment supports improved operational outcomes across supply chains.

Transitioning toward thermoforming bottom webs reduces logistics weight while maintaining durability. Recent supply chain data indicates that implementing active vacuum packaging alongside gas-flushing technologies improves puncture resistance enhancement by 25%, drastically minimizing transit losses.

By leveraging lightweight packaging construction and horizontal fill-seal machines, organizations optimize inventory stock rotation to prevent waste. Integrating shrink bag extrusion processes enhances barrier performance, enabling processors to meet stringent handling requirements while ensuring product safety.
Get Free Sample

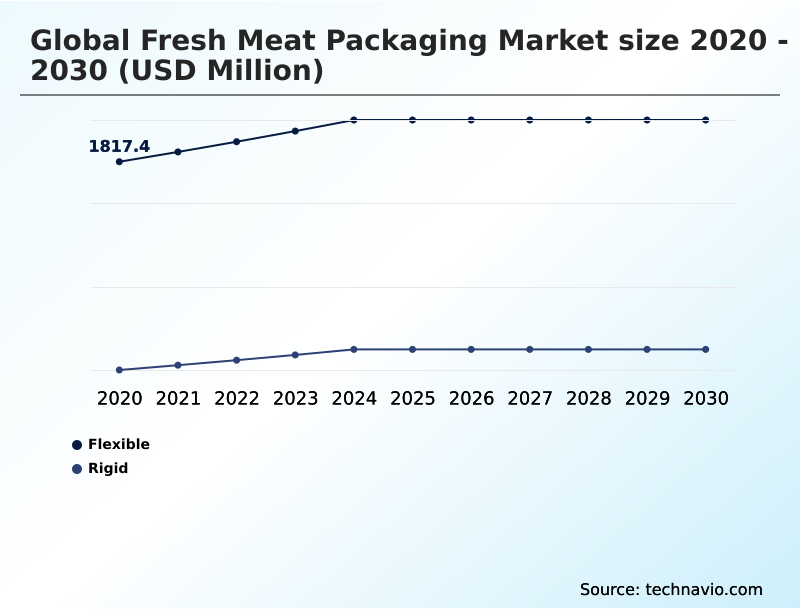
The Flexible segment was valued at USD 2.04 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 35.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
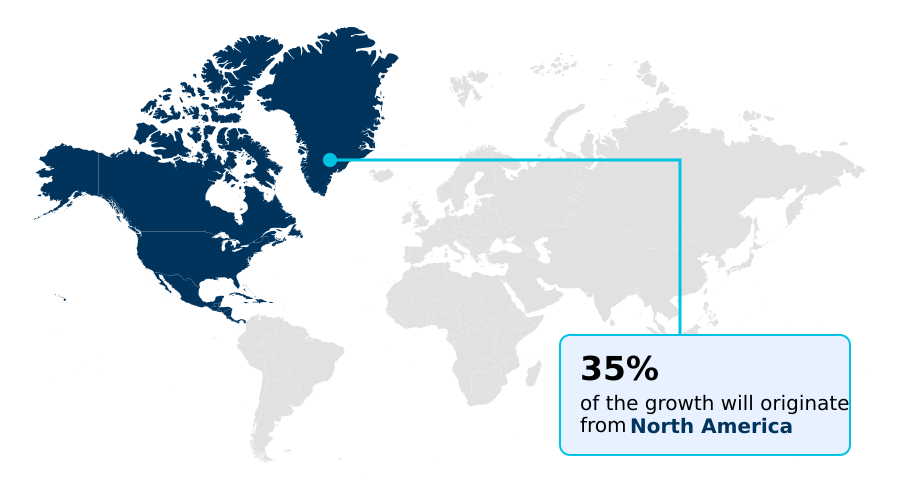
See How Fresh Meat Packaging Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Fresh Meat Packaging reveals distinct operational contrasts, particularly between North America and APAC.

North America demonstrates mature integration of modified atmosphere packaging and vacuum skin packaging, where advanced automation reduces cold chain transit losses by 14%. The region heavily prioritizes strict adherence to organized retail distribution standards to maintain shelf efficiency.

Conversely, APAC exhibits rapid modernization in its refrigerated supply chain, leading to a 20% higher adoption rate of advanced seals to support high-volume processing throughput.

While North America focuses on refining material recovery, APAC emphasizes expanding its foundational fresh protein preservation capabilities.

Both regions leverage high-barrier materials to optimize quality, though APAC processors achieve a 12% faster deployment of retail-ready meat products, corrugated leakproof boxes, and portion-controlled meat offerings to satisfy surging urban consumption and ensure robust cold chain integrity.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolving demands of the Fresh Meat Packaging require strategic adaptations in material engineering and operational planning across the supply chain. Processors are increasingly focusing on modified atmosphere meat tray sealing technologies to ensure optimal freshness during extended transit periods. This transition facilitates superior oxygen management compared to legacy wrap systems, effectively lowering contamination risks.
  • Furthermore, the integration of mono-material recyclable fresh meat films supports corporate sustainability objectives by simplifying post-consumer material recovery processes. Facilities deploying these advanced films note a 25% improvement in sorting efficiency at recycling centers, directly streamlining waste compliance functions.
  • Addressing the need for enhanced visual merchandising and preservation, vacuum skin packaging shelf life capabilities have become critical for retailers managing premium protein cuts. The tight seal minimizes liquid purge and oxidation, providing a distinct operational advantage in reducing shrink.
  • Additionally, logistics operators benefit from utilizing high-barrier flexible meat packaging pouches, which optimize pallet density and reduce transportation weight compared to rigid alternatives. Supply chain visibility has also transformed through the adoption of RFID enabled meat packaging traceability. By embedding sensor technology into labels, distributors achieve highly accurate, real-time inventory monitoring.
  • This digital oversight improves stock rotation accuracy by nearly 18%, preventing costly out-of-stock scenarios and minimizing spoilage-related losses across modern retail ecosystems.
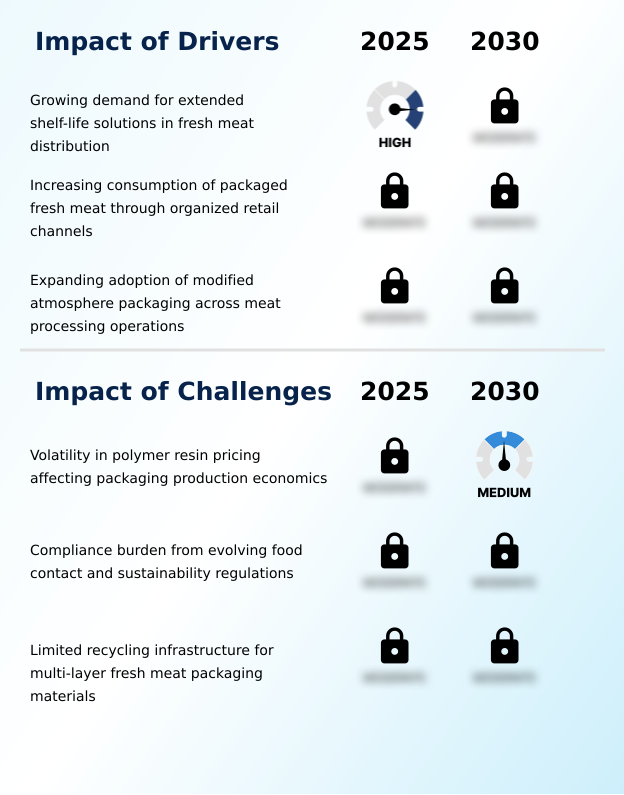
What are the key market drivers leading to the rise in the adoption of Fresh Meat Packaging Industry?

  • The escalating demand for extended shelf-life solutions across fresh meat distribution networks serves as a primary driver propelling market expansion.

  • The escalating necessity for robust preservation across expanding cross-border food logistics networks operates as a primary catalyst within the Fresh Meat Packaging.
  • As processors seek to extend geographic reach, the deployment of shelf-life extension systems has become essential to mitigate waste. Implementing automated packaging lines equipped with advanced seals ensures rigorous oxygen transmission rate control, decreasing transit-related spoilage by 21%.
  • Furthermore, integrating high-speed traysealers enhances meat processing throughput by 19%, significantly optimizing labor utilization. This operational shift toward advanced tray-sealing automation guarantees exceptional moisture variation protection and microbial growth inhibition.
  • Ultimately, utilizing these high-performance case-ready meat formats secures quality standards and satisfies surging consumer demand for conveniently packaged proteins.

What are the market trends shaping the Fresh Meat Packaging Industry?

  • The advancing transition toward mono-material and recyclable packaging formats represents a significant upcoming trend. This shift is fundamentally reshaping material selection and waste management practices within the industry ecosystem.

  • The transition toward sustainable and intelligent material formats is fundamentally reshaping the Fresh Meat Packaging ecosystem. Driven by stringent environmental mandates, manufacturers are rapidly substituting complex composites with mono-material polymer structures and fiber-based molded trays. This material shift simplifies post-consumer material recovery, improving facility recycling rates by 24%.
  • Simultaneously, the integration of RFID sensor-enabled labels and smart labeling traceability provides unprecedented digital use-by date visibility. Implementing these data-driven tracking technologies reduces sorting errors by 18% across the network. By leveraging chemical recycling integration for polyethylene terephthalate trays, processors maintain cold endurance while meeting eco-friendly mandates.
  • Consequently, these structural innovations elevate visual merchandising appeal and empower brands to achieve premium product positioning.

What challenges does the Fresh Meat Packaging Industry face during its growth?

  • Persistent volatility in polymer resin pricing severely impacts packaging production economics, constituting a major challenge to industry stability and profitability.

  • Operational stability within the Fresh Meat Packaging is persistently constrained by volatile polymer resin procurement economics and complex regulatory frameworks. Fluctuating feedstock costs severely disrupt the production of ethylene vinyl alcohol barrier materials, forcing converters to frequently recalibrate pricing models. Additionally, adapting to stringent food-contact compliance testing for multi-layer structure recyclability creates substantial administrative and technical burdens.
  • Navigating these fragmented post-consumer mandates often delays the commercialization of new bio-based compostable films and recycled polystyrene foam solutions. Transitioning legacy production lines to accommodate modern lidding film sealing requirements requires intensive capital expenditure, which can temporarily reduce overall efficiency by 15% during integration. Balancing reliable spoilage reduction tactics with mandatory circular packaging objectives remains a formidable hurdle for processors.

Exclusive Technavio Analysis on Customer Landscape

The fresh meat packaging market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the fresh meat packaging market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
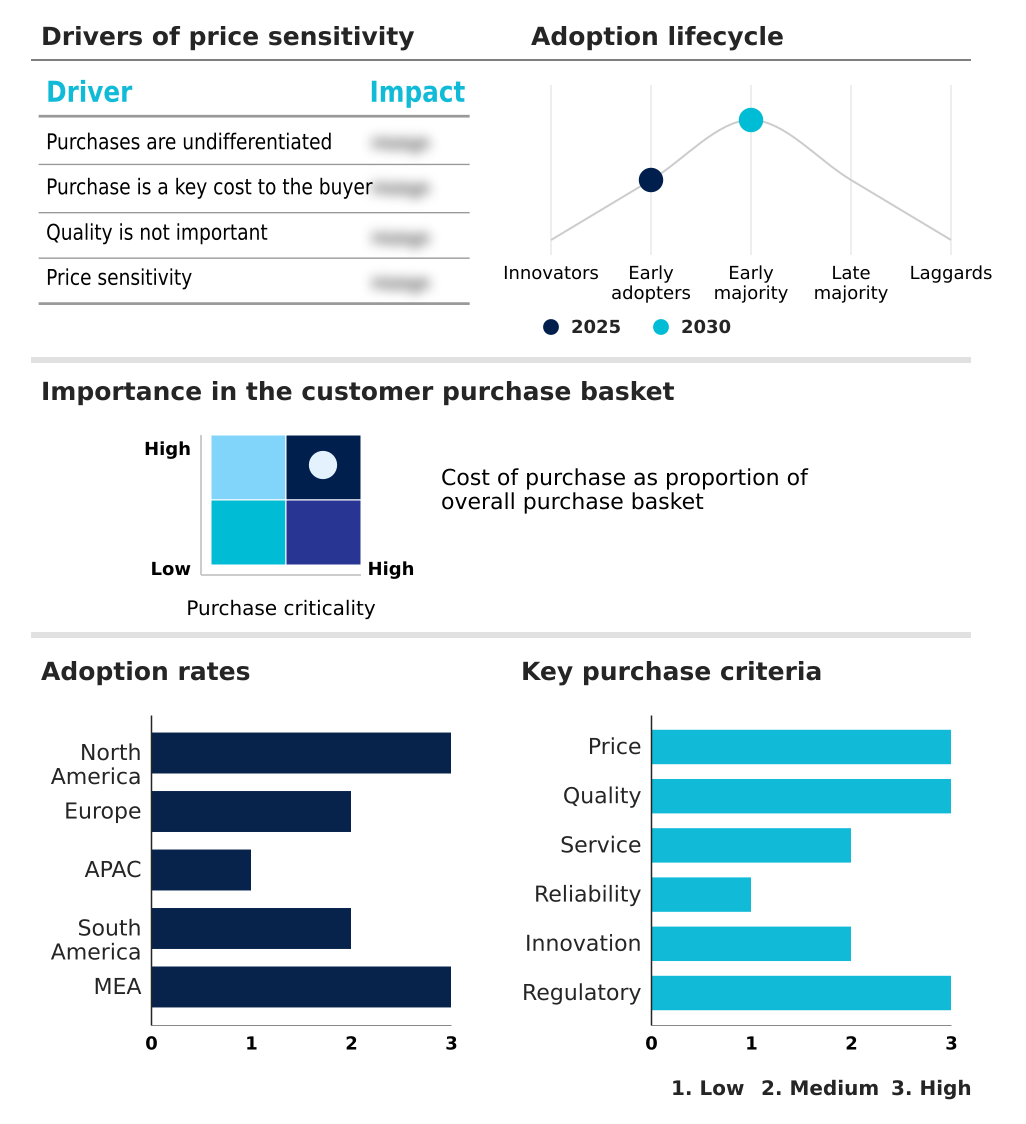
Customer Landscape of Fresh Meat Packaging Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, fresh meat packaging market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

adapa Group - The entity delivers advanced multilayer films, vacuum pouches, and customized thermoforming webs, optimizing food packaging performance for industrial applications and fresh protein preservation.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • adapa Group
  • Allvac Vakumverpackung GmbH
  • Amcor Plc
  • Coveris Management GmbH
  • DS Smith Plc
  • Faerch AS
  • FLEXOPACK SA
  • Graphic Packaging Holding Co.
  • Klockner Pentaplast Group
  • Korozo Ambalaj Sanayi ve Ticaret
  • Mondi Plc
  • MULTIVAC SE and Co. KG
  • Pactiv Evergreen Inc.
  • Plastopil Hazorea Co. Ltd.
  • Premiumpack GmbH
  • ProAmpac Holdings Inc.
  • Sealed Air Corp.
  • Smurfit Westrock plc
  • SUDPACK Holding GmbH
  • Transcontinental Inc.
  • Winpak Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Fresh meat packaging market

  • In the Metal, Glass and Plastic Containers industry, the transition toward mono-material polymer structures has improved multi-layer structure recyclability, directly impacting Fresh Meat Packaging demand by accelerating the adoption of circular packaging objectives and reducing post-consumer material waste by 30%.
  • Stringent food-contact compliance testing regulations for polymer resin procurement have forced a shift toward advanced ethylene vinyl alcohol barrier materials, directly impacting Fresh Meat Packaging supply chains by increasing the requirement for high-barrier multilayer films that ensure cold chain integrity.
  • The integration of RFID sensor-enabled labels into lightweight packaging construction has enhanced smart labeling traceability, directly impacting Fresh Meat Packaging demand by enabling retailers to track digital use-by date visibility and reduce inventory stock rotation errors by 18%.
  • Advancements in chemical recycling integration for rigid plastics have increased the availability of recycled polystyrene foam and polyethylene terephthalate trays, directly impacting Fresh Meat Packaging demand by allowing processors to meet retail-ready meat products sustainability mandates while maintaining microbial growth inhibition standards.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Fresh Meat Packaging Market insights. See full methodology.

Market Scope
Page number 312
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.7%
Market growth 2026-2030 USD 593.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 3.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, South Africa, UAE, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Fresh Meat Packaging is undergoing a structural transformation characterized by the rapid adoption of shelf-life extension systems and advanced fresh protein preservation techniques. At the boardroom level, strategic product planning is increasingly driven by circular packaging objectives, prompting a shift from traditional mixed-plastic substrates to mono-material polymer structures.
  • This pivot directly supports compliance with stringent post-consumer material recovery regulations while mitigating risks associated with volatile polymer resin procurement. Integrating tray-sealing automation and high-speed traysealers has fundamentally enhanced meat processing throughput, empowering facilities to increase production efficiency by 28% without compromising cold chain integrity.
  • Organizations are actively deploying ethylene vinyl alcohol barrier layers and bio-based compostable films to optimize oxygen transmission rate control and moisture variation protection. Furthermore, leveraging RFID sensor-enabled labels bolsters smart labeling traceability, transforming retail-ready meat products into data-rich assets. This capability improves inventory stock rotation and digital use-by date visibility, ensuring superior visual merchandising appeal.
  • Embracing chemical recycling integration for polyethylene terephthalate trays and recycled polystyrene foam further solidifies long-term supply chain resilience.

What are the Key Data Covered in this Fresh Meat Packaging Market Research and Growth Report?

  • What is the expected growth of the Fresh Meat Packaging Market between 2026 and 2030?

    • USD 593.8 million, at a CAGR of 3.7%

  • What segmentation does the market report cover?

    • The report is segmented by Packaging (Flexible, and Rigid), Type (Beef, Pork, Goat meat/mutton, Poultry, and Seafood), Material (Plastic, Paper and paperboard, Metal, Biodegradable, and Others) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Growing demand for extended shelf-life solutions in fresh meat distribution, Volatility in polymer resin pricing affecting packaging production economics

  • Who are the major players in the Fresh Meat Packaging Market?

    • adapa Group, Allvac Vakumverpackung GmbH, Amcor Plc, Coveris Management GmbH, DS Smith Plc, Faerch AS, FLEXOPACK SA, Graphic Packaging Holding Co., Klockner Pentaplast Group, Korozo Ambalaj Sanayi ve Ticaret, Mondi Plc, MULTIVAC SE and Co. KG, Pactiv Evergreen Inc., Plastopil Hazorea Co. Ltd., Premiumpack GmbH, ProAmpac Holdings Inc., Sealed Air Corp., Smurfit Westrock plc, SUDPACK Holding GmbH, Transcontinental Inc. and Winpak Ltd.

Market Research Insights

  • The Fresh Meat Packaging dynamically adapts to shifting requirements in fresh protein preservation and organized retail distribution. By implementing automated packaging lines, meat processors have achieved a 22% improvement in meat processing throughput compared to manual sealing methods. Furthermore, deploying smart labeling traceability solutions enhances digital use-by date visibility, accelerating inventory stock rotation efficiency by 16% across retail networks.
  • Firms focused on spoilage reduction tactics are increasingly integrating lightweight packaging construction to mitigate logistical burdens. Such operational refinements streamline cross-border food logistics, enabling processors to meet rigorous safety protocols while reducing material waste overheads by 11%.

We can help! Our analysts can customize this fresh meat packaging market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Packaging
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Fresh Meat Packaging Market 2020 - 2024

Historic Market Size - Data Table on Global Fresh Meat Packaging Market 2020 - 2024 ($ million)

5.2 Packaging segment analysis 2020 - 2024

Historic Market Size - Packaging Segment 2020 - 2024 ($ million)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.4 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global fresh meat packaging market

6.2 Impact of geopolitical conflicts on global fresh meat packaging market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Packaging

8.1 Market segments

Chart on Packaging - Market share 2025-2030 (%)
Data Table on Packaging - Market share 2025-2030 (%)

8.2 Comparison by Packaging

Chart on Comparison by Packaging
Data Table on Comparison by Packaging

8.3 Flexible - Market size and forecast 2025-2030

Chart on Flexible - Market size and forecast 2025-2030 ($ million)
Data Table on Flexible - Market size and forecast 2025-2030 ($ million)
Chart on Flexible - Year-over-year growth 2025-2030 (%)
Data Table on Flexible - Year-over-year growth 2025-2030 (%)

8.4 Rigid - Market size and forecast 2025-2030

Chart on Rigid - Market size and forecast 2025-2030 ($ million)
Data Table on Rigid - Market size and forecast 2025-2030 ($ million)
Chart on Rigid - Year-over-year growth 2025-2030 (%)
Data Table on Rigid - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Packaging

Market opportunity by Packaging ($ million)
Data Table on Market opportunity by Packaging ($ million)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Beef - Market size and forecast 2025-2030

Chart on Beef - Market size and forecast 2025-2030 ($ million)
Data Table on Beef - Market size and forecast 2025-2030 ($ million)
Chart on Beef - Year-over-year growth 2025-2030 (%)
Data Table on Beef - Year-over-year growth 2025-2030 (%)

9.4 Pork - Market size and forecast 2025-2030

Chart on Pork - Market size and forecast 2025-2030 ($ million)
Data Table on Pork - Market size and forecast 2025-2030 ($ million)
Chart on Pork - Year-over-year growth 2025-2030 (%)
Data Table on Pork - Year-over-year growth 2025-2030 (%)

9.5 Goat meat/mutton - Market size and forecast 2025-2030

Chart on Goat meat/mutton - Market size and forecast 2025-2030 ($ million)
Data Table on Goat meat/mutton - Market size and forecast 2025-2030 ($ million)
Chart on Goat meat/mutton - Year-over-year growth 2025-2030 (%)
Data Table on Goat meat/mutton - Year-over-year growth 2025-2030 (%)

9.6 Poultry - Market size and forecast 2025-2030

Chart on Poultry - Market size and forecast 2025-2030 ($ million)
Data Table on Poultry - Market size and forecast 2025-2030 ($ million)
Chart on Poultry - Year-over-year growth 2025-2030 (%)
Data Table on Poultry - Year-over-year growth 2025-2030 (%)

9.7 Seafood - Market size and forecast 2025-2030

Chart on Seafood - Market size and forecast 2025-2030 ($ million)
Data Table on Seafood - Market size and forecast 2025-2030 ($ million)
Chart on Seafood - Year-over-year growth 2025-2030 (%)
Data Table on Seafood - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

10. Market Segmentation by Material

10.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

10.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

10.3 Plastic - Market size and forecast 2025-2030

Chart on Plastic - Market size and forecast 2025-2030 ($ million)
Data Table on Plastic - Market size and forecast 2025-2030 ($ million)
Chart on Plastic - Year-over-year growth 2025-2030 (%)
Data Table on Plastic - Year-over-year growth 2025-2030 (%)

10.4 Paper and paperboard - Market size and forecast 2025-2030

Chart on Paper and paperboard - Market size and forecast 2025-2030 ($ million)
Data Table on Paper and paperboard - Market size and forecast 2025-2030 ($ million)
Chart on Paper and paperboard - Year-over-year growth 2025-2030 (%)
Data Table on Paper and paperboard - Year-over-year growth 2025-2030 (%)

10.5 Metal - Market size and forecast 2025-2030

Chart on Metal - Market size and forecast 2025-2030 ($ million)
Data Table on Metal - Market size and forecast 2025-2030 ($ million)
Chart on Metal - Year-over-year growth 2025-2030 (%)
Data Table on Metal - Year-over-year growth 2025-2030 (%)

10.6 Biodegradable - Market size and forecast 2025-2030

Chart on Biodegradable - Market size and forecast 2025-2030 ($ million)
Data Table on Biodegradable - Market size and forecast 2025-2030 ($ million)
Chart on Biodegradable - Year-over-year growth 2025-2030 (%)
Data Table on Biodegradable - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing demand for extended shelf-life solutions in fresh meat distribution
Increasing consumption of packaged fresh meat through organized retail channels
Expanding adoption of modified atmosphere packaging across meat processing operations

13.2 Market challenges

Volatility in polymer resin pricing affecting packaging production economics
Compliance burden from evolving food contact and sustainability regulations
Limited recycling infrastructure for multi-layer fresh meat packaging materials

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Advancing transition toward mono-material and recyclable packaging formats
Growing integration of smart labeling and traceability technologies in meat packaging
Increasing deployment of vacuum skin packaging for product visibility and waste reduction

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 adapa Group

adapa Group - Overview
adapa Group - Product / Service
adapa Group - Key offerings
SWOT

15.5 Amcor Plc

Amcor Plc - Overview
Amcor Plc - Business segments
Amcor Plc - Key news
Amcor Plc - Key offerings
Amcor Plc - Segment focus
SWOT

15.6 Coveris Management GmbH

Coveris Management GmbH - Overview
Coveris Management GmbH - Product / Service
Coveris Management GmbH - Key offerings
SWOT

15.7 DS Smith Plc

DS Smith Plc - Overview
DS Smith Plc - Product / Service
DS Smith Plc - Key news
DS Smith Plc - Key offerings
SWOT

15.8 FLEXOPACK SA

FLEXOPACK SA - Overview
FLEXOPACK SA - Product / Service
FLEXOPACK SA - Key offerings
SWOT

15.9 Graphic Packaging Holding Co.

Graphic Packaging Holding Co. - Overview
Graphic Packaging Holding Co. - Business segments
Graphic Packaging Holding Co. - Key offerings
Graphic Packaging Holding Co. - Segment focus
SWOT

15.10 Klockner Pentaplast Group

Klockner Pentaplast Group - Overview
Klockner Pentaplast Group - Product / Service
Klockner Pentaplast Group - Key offerings
SWOT

15.11 Mondi Plc

Mondi Plc - Overview
Mondi Plc - Business segments
Mondi Plc - Key news
Mondi Plc - Key offerings
Mondi Plc - Segment focus
SWOT

15.12 MULTIVAC SE and Co. KG

MULTIVAC SE and Co. KG - Overview
MULTIVAC SE and Co. KG - Product / Service
MULTIVAC SE and Co. KG - Key offerings
SWOT

15.13 Pactiv Evergreen Inc.

Pactiv Evergreen Inc. - Overview
Pactiv Evergreen Inc. - Product / Service
Pactiv Evergreen Inc. - Key offerings
SWOT

15.14 ProAmpac Holdings Inc.

ProAmpac Holdings Inc. - Overview
ProAmpac Holdings Inc. - Product / Service
ProAmpac Holdings Inc. - Key offerings
SWOT

15.15 Sealed Air Corp.

Sealed Air Corp. - Overview
Sealed Air Corp. - Business segments
Sealed Air Corp. - Key offerings
Sealed Air Corp. - Segment focus
SWOT

15.16 Smurfit Westrock plc

Smurfit Westrock plc - Overview
Smurfit Westrock plc - Business segments
Smurfit Westrock plc - Key news
Smurfit Westrock plc - Key offerings
Smurfit Westrock plc - Segment focus
SWOT

15.17 Transcontinental Inc.

Transcontinental Inc. - Overview
Transcontinental Inc. - Business segments
Transcontinental Inc. - Key news
Transcontinental Inc. - Key offerings
Transcontinental Inc. - Segment focus
SWOT

15.18 Winpak Ltd.

Winpak Ltd. - Overview
Winpak Ltd. - Business segments
Winpak Ltd. - Key offerings
Winpak Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Fresh Meat Packaging market growth will increase by USD 593.8 million during 2026-2030.

The Fresh Meat Packaging market is expected to grow at a CAGR of 3.7% during 2026-2030.

Fresh Meat Packaging market is segmented by Packaging (Flexible, Rigid) Type (Beef, Pork, Goat meat/mutton, Poultry, Seafood) Material (Plastic, Paper and paperboard, Metal, Biodegradable, Others)

adapa Group, Allvac Vakumverpackung GmbH, Amcor Plc, Coveris Management GmbH, DS Smith Plc, Faerch AS, FLEXOPACK SA, Graphic Packaging Holding Co., Klockner Pentaplast Group, Korozo Ambalaj Sanayi ve Ticaret, Mondi Plc, MULTIVAC SE and Co. KG, Pactiv Evergreen Inc., Plastopil Hazorea Co. Ltd., Premiumpack GmbH, ProAmpac Holdings Inc., Sealed Air Corp., Smurfit Westrock plc, SUDPACK Holding GmbH, Transcontinental Inc., Winpak Ltd. are a few of the key vendors in the Fresh Meat Packaging market.

North America will register the highest growth rate of 35.1% among the other regions. Therefore, the Fresh Meat Packaging market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, South Africa, UAE, Turkey, Israel

  • Growing demand for extended shelf-life solutions in fresh meat distribution is the driving factor this market.

The Fresh Meat Packaging market vendors should focus on grabbing business opportunities from the Packaging segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
