Digital Process Automation Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Digital Process Automation Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 304 Pages SKU: IRTNTR72230

Market Overview at a Glance

$12.81 B
Market Opportunity
18%
CAGR 2025 - 2030
53%
North America Growth
$6.73 B
On-premises segment 2024

Digital Process Automation Market Size 2026-2030

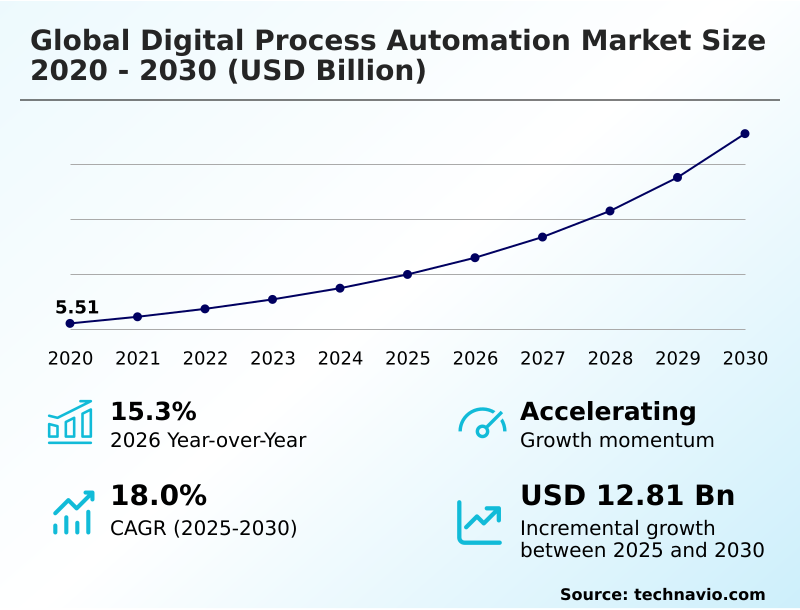
The digital process automation market size is valued to increase by USD 12.81 billion, at a CAGR of 18% from 2025 to 2030. Accelerated adoption of generative AI will drive the digital process automation market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 53% growth during the forecast period.
  • By Deployment - On-premises segment was valued at USD 6.73 billion in 2024
  • By Component - Solution segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 17.25 billion
  • Market Future Opportunities: USD 12.81 billion
  • CAGR from 2025 to 2030 : 18%

Market Summary

  • The Digital Process Automation market exhibits vigorous expansion driven by the critical necessity for organizational agility and operational resilience. Enterprises are aggressively transitioning from fragmented task execution toward comprehensive end-to-end workflow optimization.
  • A primary driver is the rapid integration of agentic artificial intelligence into enterprise digital infrastructure, enabling automated systems to process massive volumes of complex, unstructured data streams without human intervention.
  • In modern supply chain logistics, for instance, organizations utilize machine learning integration to analyze multi-tier invoices and shipping manifests, achieving a 45% improvement in processing speed compared to manual administrative methods. However, legacy infrastructure integration remains a formidable challenge. Institutions operating on monolithic mainframe architectures struggle to overlay modern event-driven architecture, causing severe bottlenecks and extending deployment timelines.
  • Despite these hurdles, incorporating predictive decision management and contextual reasoning models allows companies to elevate standard automation into autonomous decision-making systems. This structural alignment reduces operational overhead, minimizes human error, and accelerates cross-departmental visibility, ensuring sustained investment in advanced workflow orchestration platforms.

What will be the Size of the Digital Process Automation Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Digital Process Automation Market Segmented?

The digital process automation industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Deployment
    • On-premises
    • Cloud
  • Component
    • Solution
    • Service
  • End-user
    • BFSI
    • IT and telecommunication
    • Manufacturing
    • Healthcare
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Deployment Insights

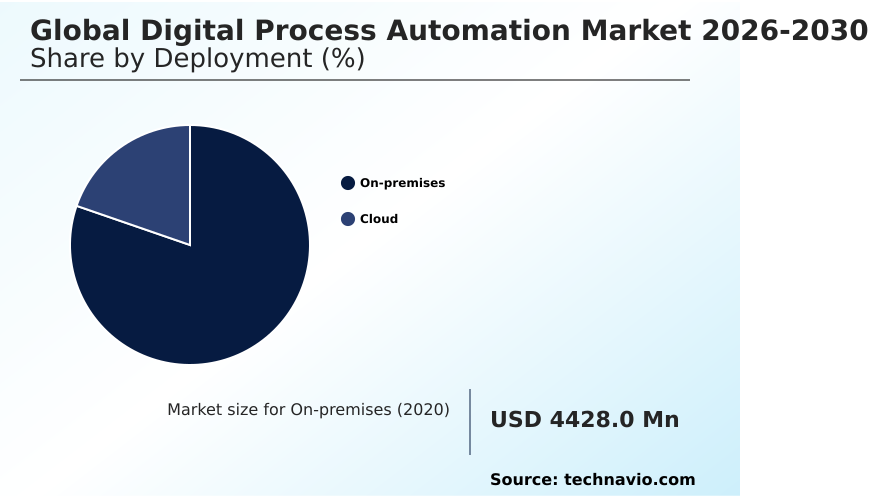
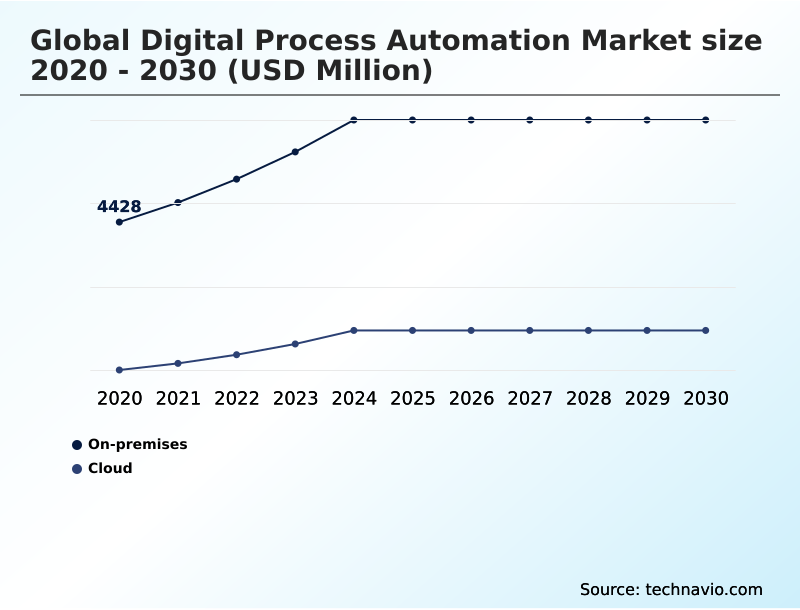
The on-premises segment is estimated to witness significant growth during the forecast period.

The on-premises segment of the Digital Process Automation market serves as critical infrastructure for highly regulated sectors requiring absolute data control.

Institutions leverage on-premises deployments to enforce zero-trust security models while maintaining logical isolation from external networks, which minimizes exposure to multi-tenant vulnerabilities. Implementing robust continuous process governance directly onto internal hardware environments allows organizations to process sensitive information securely.

By integrating intelligent document processing and cognitive workflow execution on-site, enterprises experience a 25% improvement in automated exception handling compared to legacy methods.

Furthermore, executing predictive decision management within localized servers enhances data sovereignty protocols, resulting in a 40% reduction in compliance reporting errors.

This localized approach empowers technology divisions with complete operational autonomy over enterprise architecture management and mainframe modernization, ensuring seamless legacy infrastructure integration without introducing external network latency.
Get Free Sample

The On-premises segment was valued at USD 6.73 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 53% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
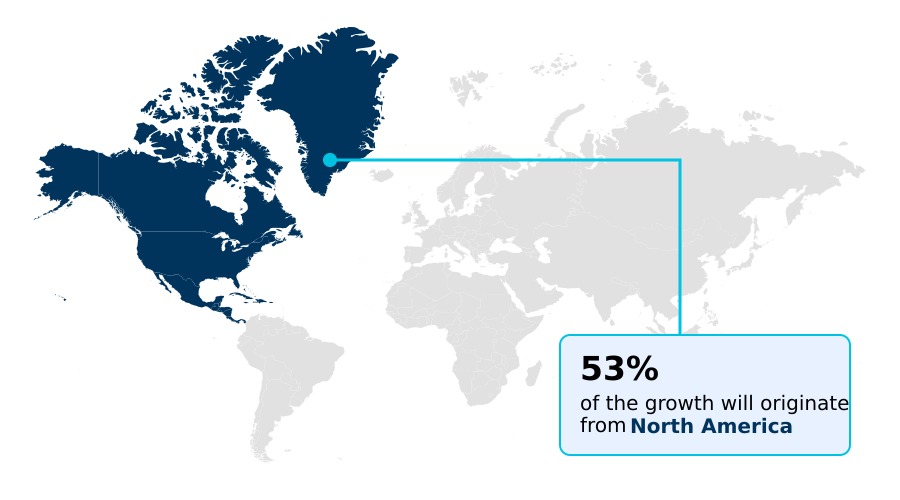
See How Digital Process Automation Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Digital Process Automation market highlights stark contrasts in regional maturity and deployment strategies. North America dominates adoption, driven by robust low-code orchestration and stringent regulatory compliance reporting mandates in the financial sector.

Organizations in the United States utilize process intelligence analytics and robotic process automation to streamline complex operations, achieving a 35% higher penetration rate in process optimization compared to European counterparts.

Conversely, Europe accelerates its deployment primarily to enforce privacy regulations, utilizing robust auditability frameworks that result in a 20% reduction in compliance-related penalties.

While North American enterprises prioritize omnichannel experience optimization for customer retention, European firms focus heavily on digital operational resilience.

This divergence demonstrates how regulatory landscapes dictate the adoption of hyperautomation strategies, compelling global corporations to tailor their digital initiatives to address distinct regional challenges and operational scaling requirements.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The relentless pursuit of enterprise agility has fundamentally transformed the Digital Process Automation market, elevating basic task execution to sophisticated operational orchestration. Large-scale organizations are increasingly transitioning away from fragmented legacy tools to deploy robust low-code workflow orchestration platforms. This architectural shift enables business units to map, execute, and monitor end-to-end workflows with unprecedented speed.
  • A critical component of this evolution is the integration of intelligent document processing automation solutions, which empower companies to rapidly ingest and contextualize massive volumes of unstructured data. Within supply chain compliance functions, for instance, utilizing cognitive data processing workflow engines yields a 45% higher accuracy rate in contract validation compared to manual oversight.
  • Furthermore, navigating complex regulatory environments demands innovative approaches to technical debt; hence, enterprises are investing heavily in legacy infrastructure modernization automation tools. These specialized solutions bridge the gap between outdated monolithic mainframes and modern cloud environments, mitigating the severe bottlenecks that traditionally hampered digital transformation.
  • As workflows become increasingly complex, organizations are adopting agentic artificial intelligence process execution to handle dynamic decision pathways autonomously. This cognitive capability allows systems to analyze historical data, predict operational friction, and execute routing adjustments instantly.
  • By upgrading to these intelligent frameworks, corporations achieve a 30% reduction in administrative overhead, positioning advanced process orchestration as a critical necessity for maintaining competitive resilience in a digitized landscape.
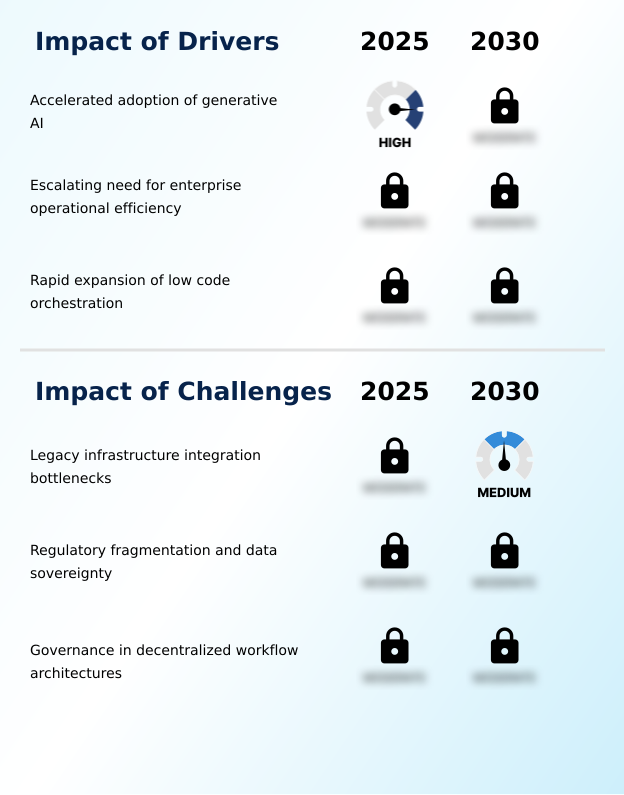
What are the key market drivers leading to the rise in the adoption of Digital Process Automation Industry?

  • The accelerated adoption of generative AI serves as a primary catalyst propelling expansion across the market.

  • The aggressive integration of agentic artificial intelligence into enterprise software architecture operates as a primary catalyst propelling the Digital Process Automation market. Legacy systems reliant on rigid logic require continuous manual reconfiguration, creating severe productivity bottlenecks within supply chain logistics.
  • By leveraging machine learning integration and process mining algorithms, modern platforms elevate standard automation into autonomous decision-making systems. This capability, powered by semantic intent recognition, empowers organizations to analyze massive data volumes and execute cognitive routing decisions instantly.
  • Implementing these predictive frameworks yields a 40% reduction in operational cycle times and a 20% improvement in customer onboarding acceleration.
  • This profound shift enables enterprises to achieve higher throughput and operational resilience, ensuring continuous digital transformation initiatives remain a top boardroom priority for long-term scalability.

What are the market trends shaping the Digital Process Automation Industry?

  • Intelligent document processing is modernizing enterprise workflows and emerging as a prominent market trend. This technological advancement significantly optimizes data extraction and operational efficiency.

  • The convergence of computer vision and natural language processing is rapidly modernizing enterprise workflows, establishing advanced automation as a dominant operational trend. Multinational corporations are actively replacing legacy optical character recognition tools with advanced vision language architectures capable of interpreting unstructured data processing inputs without predefined templates.
  • This technological shift enables systems to extract critical fields from complex medical records and multi-currency invoices automatically. By implementing contextual reasoning models, organizations experience a 45% reduction in document processing times and a 30% decrease in manual data entry errors. This transformation fundamentally enhances cross-departmental visibility, allowing administrative teams to achieve complete end-to-end workflow optimization.
  • Consequently, embedding these capabilities directly into business process management ecosystems accelerates transaction turnaround acceleration, driving a 25% improvement in overall workflow interoperability and operational throughput.

What challenges does the Digital Process Automation Industry face during its growth?

  • Legacy infrastructure integration bottlenecks present a significant structural challenge constraining broader industry adoption.

  • The seamless integration of modern automation platforms into monolithic enterprise digital infrastructure presents a major structural impediment. Large corporate organizations frequently operate on legacy operational software that predates modern event-driven architecture, creating severe friction during digital modernization. Attempting to overlay cloud native deployments across older mainframe databases introduces extreme complexity and system instability.
  • Developing custom middleware for microservices-based automation extends initial deployment timetables significantly, severely hindering technical debt reduction and resulting in a 35% increase in unanticipated IT maintenance costs. Furthermore, these disconnected data flows cause processing latency within decentralized workflow architectures, reducing automated data classification efficiency by 25%.
  • Until software providers deliver standardized integration pathways for hybrid cloud environments, critical functions like dynamic case management and anti-money laundering verification will continue to constrain broad automation rollouts.

Exclusive Technavio Analysis on Customer Landscape

The digital process automation market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the digital process automation market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
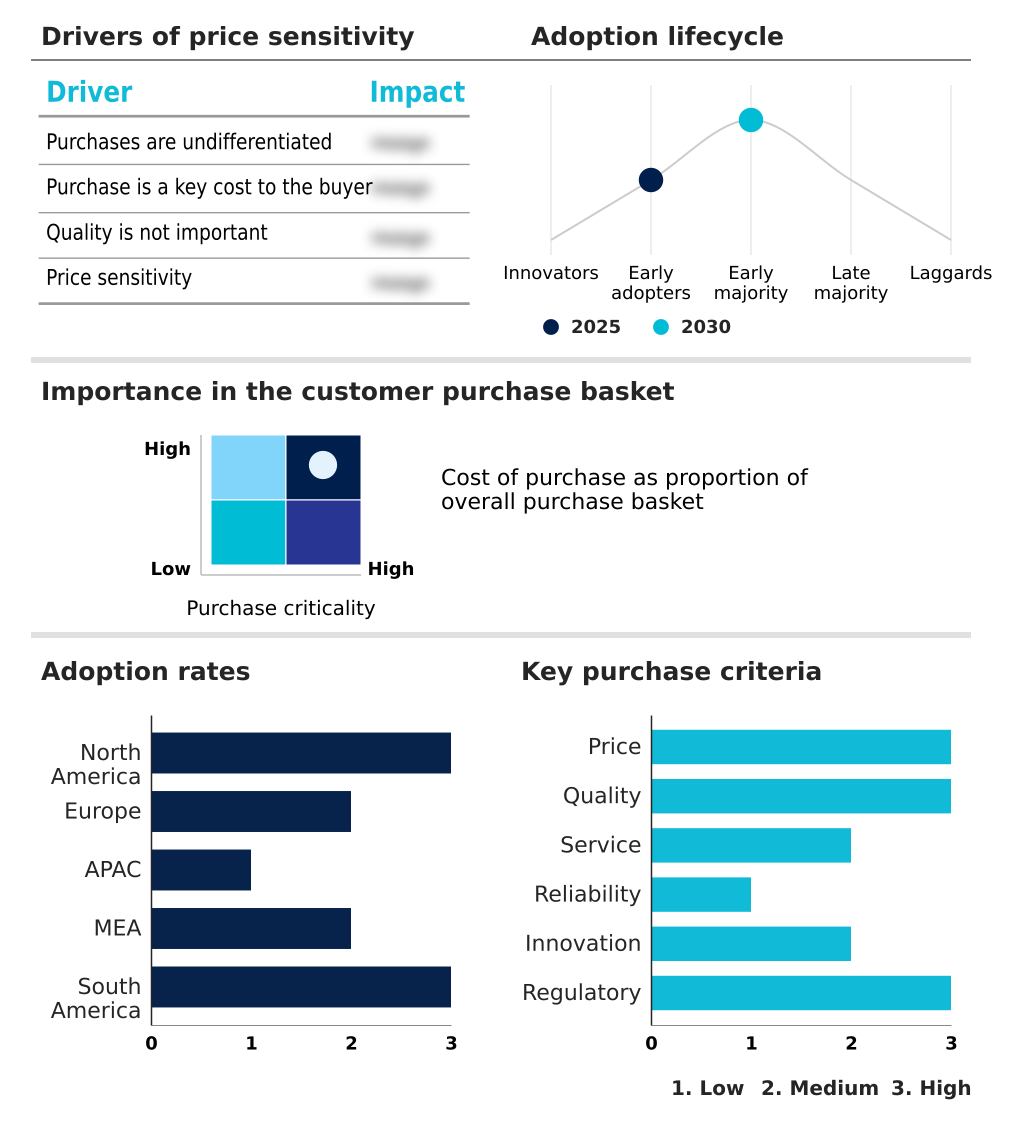
Customer Landscape of Digital Process Automation Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, digital process automation market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Appian Corp. - The provider delivers a comprehensive low-code platform integrating process orchestration and robotic process automation to accelerate digital transformation and build enterprise-grade applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Appian Corp.
  • Automation Anywhere Inc.
  • Bizagi Group Ltd.
  • Camunda Services GmbH
  • Creatio Ltd.
  • Genpact Ltd.
  • IBM Corp.
  • Kissflow Inc.
  • Microsoft Corp.
  • Newgen Software Technologies
  • Nintex Global Ltd.
  • Open Text Corp.
  • Oracle Corp.
  • Pegasystems Inc.
  • Salesforce Inc.
  • SAP SE
  • ServiceNow Inc.
  • Tungsten Automation Corp.
  • UiPath Inc.
  • Workato Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Digital process automation market

  • In the Systems Software industry, the widespread adoption of zero-trust security models has forced enterprises to re-evaluate their access controls, directly impacting Digital Process Automation demand by accelerating the integration of encrypted automated data classification engines that reduce unauthorized access incidents by 35%.
  • Strict regulatory mandates under the Digital Operational Resilience Act have compelled financial institutions to upgrade auditability frameworks, creating an immediate need for dynamic case management tools that improve regulatory compliance reporting efficiency by 40% across decentralized workflow architectures.
  • The transition toward cloud native deployments and microservices-based automation has disrupted traditional monolithic software architectures, driving a 50% increase in the utilization of low-code orchestration platforms designed to enhance workflow interoperability within hybrid cloud environments.
  • Advancements in vision language architectures have fundamentally transformed how unstructured data is analyzed at scale, fueling the adoption of intelligent document processing automation solutions that accelerate cognitive routing decisions and improve transaction turnaround acceleration by up to 60%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Digital Process Automation Market insights. See full methodology.

Market Scope
Page number 304
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 18%
Market growth 2026-2030 USD 12807.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 15.3%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Digital Process Automation market is undergoing a profound structural evolution as enterprises replace rigid, rule-based systems with adaptable, intelligent workflow orchestration engines. Organizations are increasingly deploying low-code orchestration to democratize application development, empowering business analysts to design and optimize complex operational channels without deep technical expertise.
  • A major catalyst in this landscape is the deep integration of natural language processing and vision language architectures, which fundamentally modernize unstructured data processing. By incorporating these cognitive technologies into core supply chain planning, enterprises achieve a 35% reduction in multi-tier invoice processing time compared to traditional manual methods.
  • Furthermore, the reliance on process intelligence analytics enables corporate leadership to visualize operational bottlenecks instantly and refine strategic product planning. Deploying dynamic case management and semantic intent recognition allows financial institutions to navigate stringent regulatory environments efficiently while maintaining flawless audit records.
  • This transition toward autonomous decision-making systems transforms standard administrative tasks into intelligent, self-optimizing operations, cementing advanced process orchestration as indispensable infrastructure for sustainable enterprise agility.

What are the Key Data Covered in this Digital Process Automation Market Research and Growth Report?

  • What is the expected growth of the Digital Process Automation Market between 2026 and 2030?

    • USD 12.81 billion, at a CAGR of 18%

  • What segmentation does the market report cover?

    • The report is segmented by Deployment (On-premises, and Cloud), Component (Solution, and Service), End-user (BFSI, IT and telecommunication, Manufacturing, Healthcare, and Others) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Accelerated adoption of generative AI, Legacy infrastructure integration bottlenecks

  • Who are the major players in the Digital Process Automation Market?

    • Appian Corp., Automation Anywhere Inc., Bizagi Group Ltd., Camunda Services GmbH, Creatio Ltd., Genpact Ltd., IBM Corp., Kissflow Inc., Microsoft Corp., Newgen Software Technologies, Nintex Global Ltd., Open Text Corp., Oracle Corp., Pegasystems Inc., Salesforce Inc., SAP SE, ServiceNow Inc., Tungsten Automation Corp., UiPath Inc. and Workato Inc.

Market Research Insights

  • The Digital Process Automation market reflects a profound transition toward intelligent end-to-end workflow optimization. Modern enterprises rely on advanced workflow interoperability to streamline back-office operations and enhance cross-departmental visibility. By embedding cognitive tools into existing enterprise digital infrastructure, organizations have reported a 30% reduction in manual data entry errors.
  • Furthermore, the deployment of hyperautomation strategies within complex supply chain operations yields a 25% acceleration in transaction turnaround times. Implementing robust auditability frameworks also ensures alignment with strict compliance mandates, resulting in a 40% improvement in regulatory compliance reporting accuracy. This relentless focus on technical debt reduction and continuous process governance ensures sustained operational agility across digitized corporate ecosystems.

We can help! Our analysts can customize this digital process automation market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Component
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Digital Process Automation Market 2020 - 2024

Historic Market Size - Data Table on Global Digital Process Automation Market 2020 - 2024 ($ million)

5.2 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.3 Component segment analysis 2020 - 2024

Historic Market Size - Component Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Digital Process Automation Market

6.2 Impact of geopolitical conflicts on Global Digital Process Automation Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Deployment

8.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

8.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

8.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

8.4 Cloud - Market size and forecast 2025-2030

Chart on Cloud - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud - Market size and forecast 2025-2030 ($ million)
Chart on Cloud - Year-over-year growth 2025-2030 (%)
Data Table on Cloud - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

9. Market Segmentation by Component

9.1 Market segments

Chart on Component - Market share 2025-2030 (%)
Data Table on Component - Market share 2025-2030 (%)

9.2 Comparison by Component

Chart on Comparison by Component
Data Table on Comparison by Component

9.3 Solution - Market size and forecast 2025-2030

Chart on Solution - Market size and forecast 2025-2030 ($ million)
Data Table on Solution - Market size and forecast 2025-2030 ($ million)
Chart on Solution - Year-over-year growth 2025-2030 (%)
Data Table on Solution - Year-over-year growth 2025-2030 (%)

9.4 Service - Market size and forecast 2025-2030

Chart on Service - Market size and forecast 2025-2030 ($ million)
Data Table on Service - Market size and forecast 2025-2030 ($ million)
Chart on Service - Year-over-year growth 2025-2030 (%)
Data Table on Service - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Component

Market opportunity by Component ($ million)
Data Table on Market opportunity by Component ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 BFSI - Market size and forecast 2025-2030

Chart on BFSI - Market size and forecast 2025-2030 ($ million)
Data Table on BFSI - Market size and forecast 2025-2030 ($ million)
Chart on BFSI - Year-over-year growth 2025-2030 (%)
Data Table on BFSI - Year-over-year growth 2025-2030 (%)

10.4 IT and telecommunication - Market size and forecast 2025-2030

Chart on IT and telecommunication - Market size and forecast 2025-2030 ($ million)
Data Table on IT and telecommunication - Market size and forecast 2025-2030 ($ million)
Chart on IT and telecommunication - Year-over-year growth 2025-2030 (%)
Data Table on IT and telecommunication - Year-over-year growth 2025-2030 (%)

10.5 Manufacturing - Market size and forecast 2025-2030

Chart on Manufacturing - Market size and forecast 2025-2030 ($ million)
Data Table on Manufacturing - Market size and forecast 2025-2030 ($ million)
Chart on Manufacturing - Year-over-year growth 2025-2030 (%)
Data Table on Manufacturing - Year-over-year growth 2025-2030 (%)

10.6 Healthcare - Market size and forecast 2025-2030

Chart on Healthcare - Market size and forecast 2025-2030 ($ million)
Data Table on Healthcare - Market size and forecast 2025-2030 ($ million)
Chart on Healthcare - Year-over-year growth 2025-2030 (%)
Data Table on Healthcare - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Accelerated adoption of generative AI
Escalating need for enterprise operational efficiency
Rapid expansion of low code orchestration

13.2 Market challenges

Legacy infrastructure integration bottlenecks
Regulatory fragmentation and data sovereignty
Governance in decentralized workflow architectures

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Intelligent document processing modernizing enterprise workflows
Omnichannel experience optimization driving process automation
Cybersecurity modernization accelerating process automation adoption

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Appian Corp.

Appian Corp. - Overview
Appian Corp. - Business segments
Appian Corp. - Key offerings
Appian Corp. - Segment focus
SWOT

15.5 Automation Anywhere Inc.

Automation Anywhere Inc. - Overview
Automation Anywhere Inc. - Product / Service
Automation Anywhere Inc. - Key offerings
SWOT

15.6 Camunda Services GmbH

Camunda Services GmbH - Overview
Camunda Services GmbH - Product / Service
Camunda Services GmbH - Key offerings
SWOT

15.7 Genpact Ltd.

Genpact Ltd. - Overview
Genpact Ltd. - Business segments
Genpact Ltd. - Key news
Genpact Ltd. - Key offerings
Genpact Ltd. - Segment focus
SWOT

15.8 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.9 Microsoft Corp.

Microsoft Corp. - Overview
Microsoft Corp. - Business segments
Microsoft Corp. - Key news
Microsoft Corp. - Key offerings
Microsoft Corp. - Segment focus
SWOT

15.10 Newgen Software Technologies

Newgen Software Technologies - Overview
Newgen Software Technologies - Product / Service
Newgen Software Technologies - Key offerings
SWOT

15.11 Open Text Corp.

Open Text Corp. - Overview
Open Text Corp. - Business segments
Open Text Corp. - Key news
Open Text Corp. - Key offerings
Open Text Corp. - Segment focus
SWOT

15.12 Oracle Corp.

Oracle Corp. - Overview
Oracle Corp. - Business segments
Oracle Corp. - Key news
Oracle Corp. - Key offerings
Oracle Corp. - Segment focus
SWOT

15.13 Pegasystems Inc.

Pegasystems Inc. - Overview
Pegasystems Inc. - Business segments
Pegasystems Inc. - Key offerings
Pegasystems Inc. - Segment focus
SWOT

15.14 Salesforce Inc.

Salesforce Inc. - Overview
Salesforce Inc. - Business segments
Salesforce Inc. - Key news
Salesforce Inc. - Key offerings
Salesforce Inc. - Segment focus
SWOT

15.15 SAP SE

SAP SE - Overview
SAP SE - Business segments
SAP SE - Key news
SAP SE - Key offerings
SAP SE - Segment focus
SWOT

15.16 ServiceNow Inc.

ServiceNow Inc. - Overview
ServiceNow Inc. - Product / Service
ServiceNow Inc. - Key news
ServiceNow Inc. - Key offerings
SWOT

15.17 UiPath Inc.

UiPath Inc. - Overview
UiPath Inc. - Product / Service
UiPath Inc. - Key news
UiPath Inc. - Key offerings
SWOT

15.18 Workato Inc.

Workato Inc. - Overview
Workato Inc. - Product / Service
Workato Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Digital Process Automation market growth will increase by USD 12807.1 million during 2026-2030.

The Digital Process Automation market is expected to grow at a CAGR of 18% during 2026-2030.

Digital Process Automation market is segmented by Deployment (On-premises, Cloud) Component (Solution, Service) End-user (BFSI, IT and telecommunication, Manufacturing, Healthcare, Others)

Appian Corp., Automation Anywhere Inc., Bizagi Group Ltd., Camunda Services GmbH, Creatio Ltd., Genpact Ltd., IBM Corp., Kissflow Inc., Microsoft Corp., Newgen Software Technologies, Nintex Global Ltd., Open Text Corp., Oracle Corp., Pegasystems Inc., Salesforce Inc., SAP SE, ServiceNow Inc., Tungsten Automation Corp., UiPath Inc., Workato Inc. are a few of the key vendors in the Digital Process Automation market.

North America will register the highest growth rate of 53% among the other regions. Therefore, the Digital Process Automation market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Accelerated adoption of generative AI is the driving factor this market.

The Digital Process Automation market vendors should focus on grabbing business opportunities from the Deployment segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
