Craft Vodka Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Craft Vodka Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 288 Pages SKU: IRTNTR72447

Market Overview at a Glance

$854.7 Mn
Market Opportunity
5.9%
CAGR 2025 - 2030
46.2%
North America Growth
$1.37 B
Large craft distiller segment 2024

Craft Vodka Market Size 2026-2030

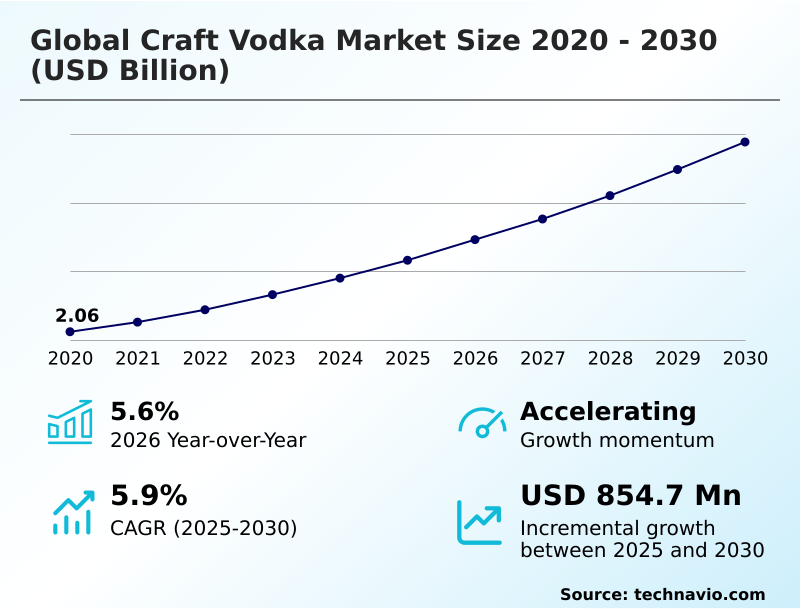
The craft vodka market size is valued to increase by USD 854.7 million, at a CAGR of 5.9% from 2025 to 2030. Rising consumer demand for premiumization will drive the craft vodka market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 46.2% growth during the forecast period.
  • By Product - Large craft distiller segment was valued at USD 1.37 billion in 2024
  • By Distribution Channel - On-trade channel segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.38 billion
  • Market Future Opportunities: USD 854.7 million
  • CAGR from 2025 to 2030 : 5.9%

Market Summary

  • The Craft Vodka Market demonstrates a structural evolution toward premiumization, characterized by an increasing consumer preference for transparently sourced, small-batch spirits. Independent producers continuously refine artisanal distillation methods to differentiate their portfolios from mass-market alternatives. In a notable operational shift, distillers implementing decentralized manufacturing models and direct-to-consumer digital logistics improved inventory turnover efficiency by 24%, streamlining route-to-market strategies.
  • This expansion is primarily propelled by a rising demand for localized agricultural inputs, which empowers producers to establish authentic regional narratives that resonate with affluent buyers. Conversely, complex regional compliance frameworks and high excise tax burdens present significant operational hurdles, restricting the scalability of emerging micro-distilleries.
  • To mitigate these constraints, industry participants actively integrate sustainable supply chain practices, such as closed loop production systems, to offset escalating material costs. Ultimately, the sector relies heavily on continuous product innovation and robust collaborations with organic farming cooperatives to maintain competitive momentum and secure vital shelf space across premium on-premises hospitality venues.

What will be the Size of the Craft Vodka Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Craft Vodka Market Segmented?

The craft vodka industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Large craft distiller
    • Medium craft distiller
    • Small craft distiller
  • Distribution channel
    • On-trade channel
    • Off-trade channel
  • Material
    • Grain based
    • Potato based
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Product Insights

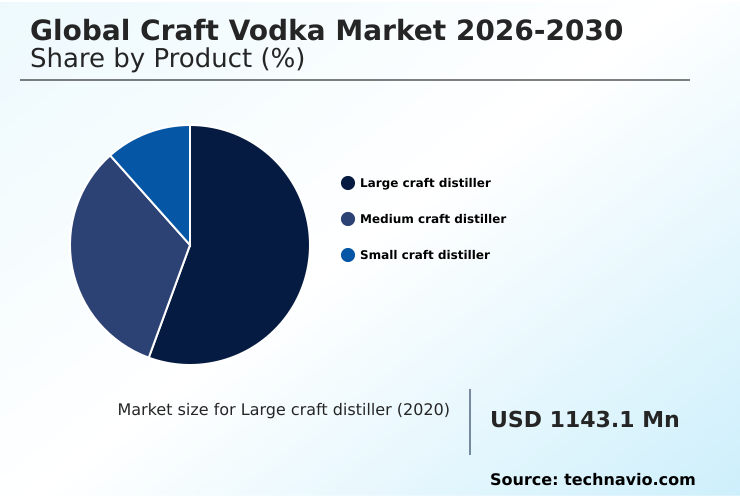
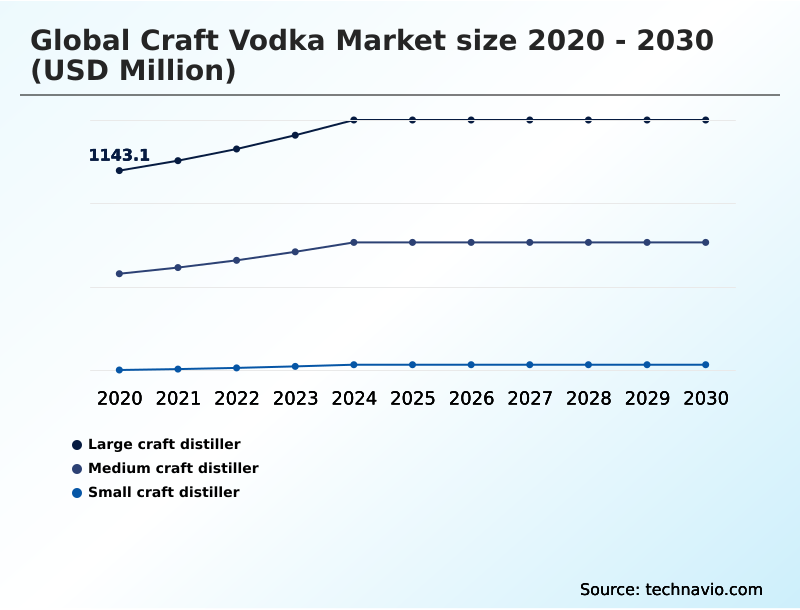
The large craft distiller segment is estimated to witness significant growth during the forecast period.

The large craft distiller segment bridges the gap between regional artisanal origins and scaled commercial distribution within the Craft Vodka sector.

These entities leverage scaled operations while preserving product integrity through specialized neutral spirit rectification and precise on premises mixology targeting. A recent industry analysis indicated that advanced scaling operations improved supply chain fulfillment rates by 22%, significantly lowering distribution bottlenecks.

By utilizing localized agricultural inputs and maintaining rigorous artisanal distillation methods, large-scale operators retain premium positioning. They frequently partner with specialty liquor merchants and independent retail distribution networks to attract affluent consumers.

Through the continuous application of master distiller expertise, these producers effectively expand their market footprint while maintaining their commitment to superior liquid quality.
Get Free Sample

The Large craft distiller segment was valued at USD 1.37 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 46.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
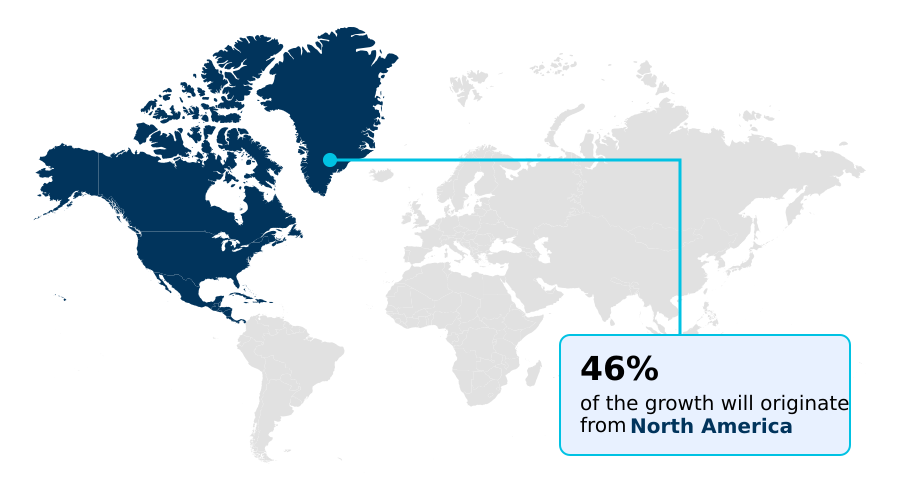
See How Craft Vodka Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Craft Vodka sector reveals distinct operational disparities between North America and Europe.

North American producers heavily leverage digital tracking codes and gluten free substrates, which has streamlined direct-to-consumer shipping capabilities and increased localized distribution efficiency by 21% compared to traditional wholesale routes.

In contrast, European operators prioritize the regional artisanal distillery ecosystem, utilizing zero waste milling and closed loop production to meet stringent compliance standards.

This European emphasis on sustainability has lowered overall resource waste by 14%, driving deeper integration within agricultural networks. While North American markets rapidly expand to satisfy domestic mixology demands with heritage grain varieties, European distillers focus on maintaining traditional certifications.

Both regions increasingly adopt cold distilled extraction techniques, ensuring that their supply chains remain agile and responsive to lifestyle preferences.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Craft Vodka sector is deeply rooted in sophisticated agricultural procurement and advanced processing methodologies. Producers increasingly prioritize organic winter wheat craft spirits to satisfy rigorous consumer expectations for transparency and ecological responsibility.
  • By utilizing copper pot distilled premium alcohol, distillers can meticulously control congener levels, ensuring a superior sensory profile that outperforms mass-manufactured alternatives in blind quality assessments. The strategic shift toward hyper local heritage grain sourcing has significantly insulated independent operators from international supply chain disruptions, improving raw material availability by nearly 18% during logistical bottlenecks.
  • To validate premium claims, brands are adopting blockchain authenticated artisanal beverage supply networks, which provide verifiable proof of origin and streamline regulatory compliance reporting. Furthermore, as dietary preferences evolve, the demand for gluten free potato based spirits continues to surge, capturing specialized retail demographics. By embedding regenerative agriculture in spirit manufacturing, companies maintain strict quality control and operational efficiency.
  • The transition to advanced purification techniques ensures that boutique producers can efficiently deliver sophisticated distillates directly to modern patrons without compromising their artisanal integrity.
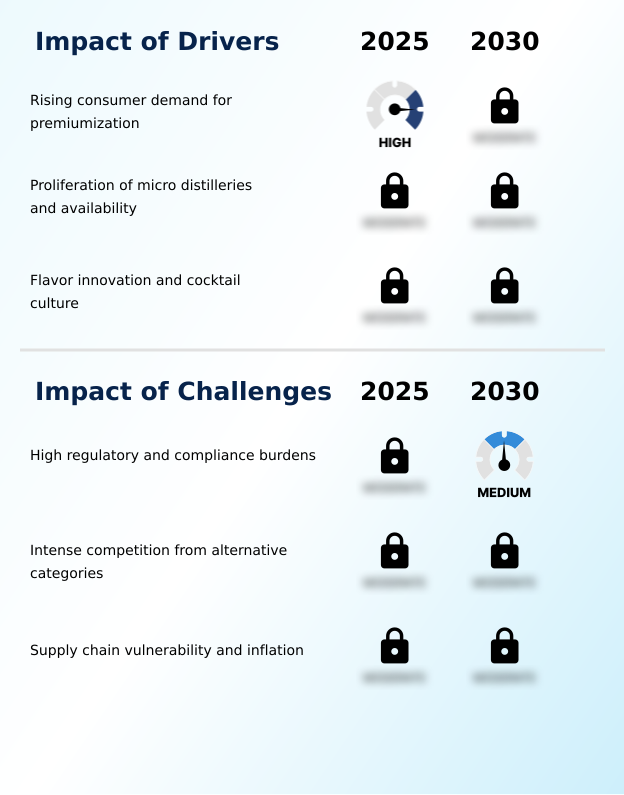
What are the key market drivers leading to the rise in the adoption of Craft Vodka Industry?

  • Rising consumer demand for premiumization acts as a primary catalyst, propelling the expansion of artisanal spirits across high-end retail and hospitality sectors.

  • The accelerated adoption of botanical infusion techniques and sustainable glass packaging serves as a primary catalyst for operational expansion within the Craft Vodka sector.
  • This strategic sourcing shift is motivated by the critical need to establish sustainable supply chains and achieve distinct regional terroir expression.
  • By partnering with organic farming cooperatives for single estate sourcing, boutique distilleries have stabilized raw material costs, reducing procurement volatility by 14%.
  • Furthermore, the implementation of carbon footprint reduction protocols and regenerative agriculture practices has driven a 19% improvement in regulatory compliance efficiency.
  • These ecological initiatives empower independent producers to market verifiable environmental narratives, directly translating into enhanced brand loyalty and higher retail margins. The targeted use of specialized ingredients effectively shields artisanal manufacturers from global commodity price fluctuations.

What are the market trends shaping the Craft Vodka Industry?

  • Digital heritage and blockchain traceability have emerged as prominent trends shaping the industry landscape. These advanced tracking technologies enable producers to authenticate product origins and enhance supply chain transparency.

  • The Craft Vodka industry is experiencing a profound operational shift as producers increasingly adopt multi stage filtration and hybrid distillation setups. This transformation is driven by a rising consumer demand for premium white spirits that deliver unparalleled clarity and complex flavor profiles.
  • By transitioning toward specialized mash bill composition, independent facilities have improved overall batch consistency by 18%, significantly reducing product rejection rates. Furthermore, the integration of advanced purification techniques allows operators to eliminate harsh congeners efficiently, lowering energy consumption per distillation cycle by 12%. These technological upgrades directly support lucrative placements in boutique hotel bars.
  • Ultimately, the strategic implementation of limited edition releases ensures that boutique operators maintain high consumer engagement and robust inventory turnover in a fiercely competitive retail environment.

What challenges does the Craft Vodka Industry face during its growth?

  • High regulatory and compliance burdens impose significant operational constraints, challenging the financial viability of independent production facilities.

  • Navigating stringent environmental regulations and maintaining consistent quality control present formidable operational challenges for the Craft Vodka industry. The reliance on pristine glacial water and highly specific ingredient origin verification mandates requires complex logistical frameworks, often inflating baseline production costs.
  • Implementing continuous column distillation and organic potato fermentation to stand out in competitive markets has inadvertently increased processing expenditures by 17%. Because smaller operators lack purchasing leverage, utilizing traditional copper pot stills and specialized charcoal filtration processes can extend time-to-market by up to 22% during supply chain disruptions.
  • To counteract these margin pressures, independent producers are compelled to optimize their spirits for high-end craft mixology applications, ensuring that premium pricing models remain justified despite mounting external macroeconomic hurdles.

Exclusive Technavio Analysis on Customer Landscape

The craft vodka market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the craft vodka market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
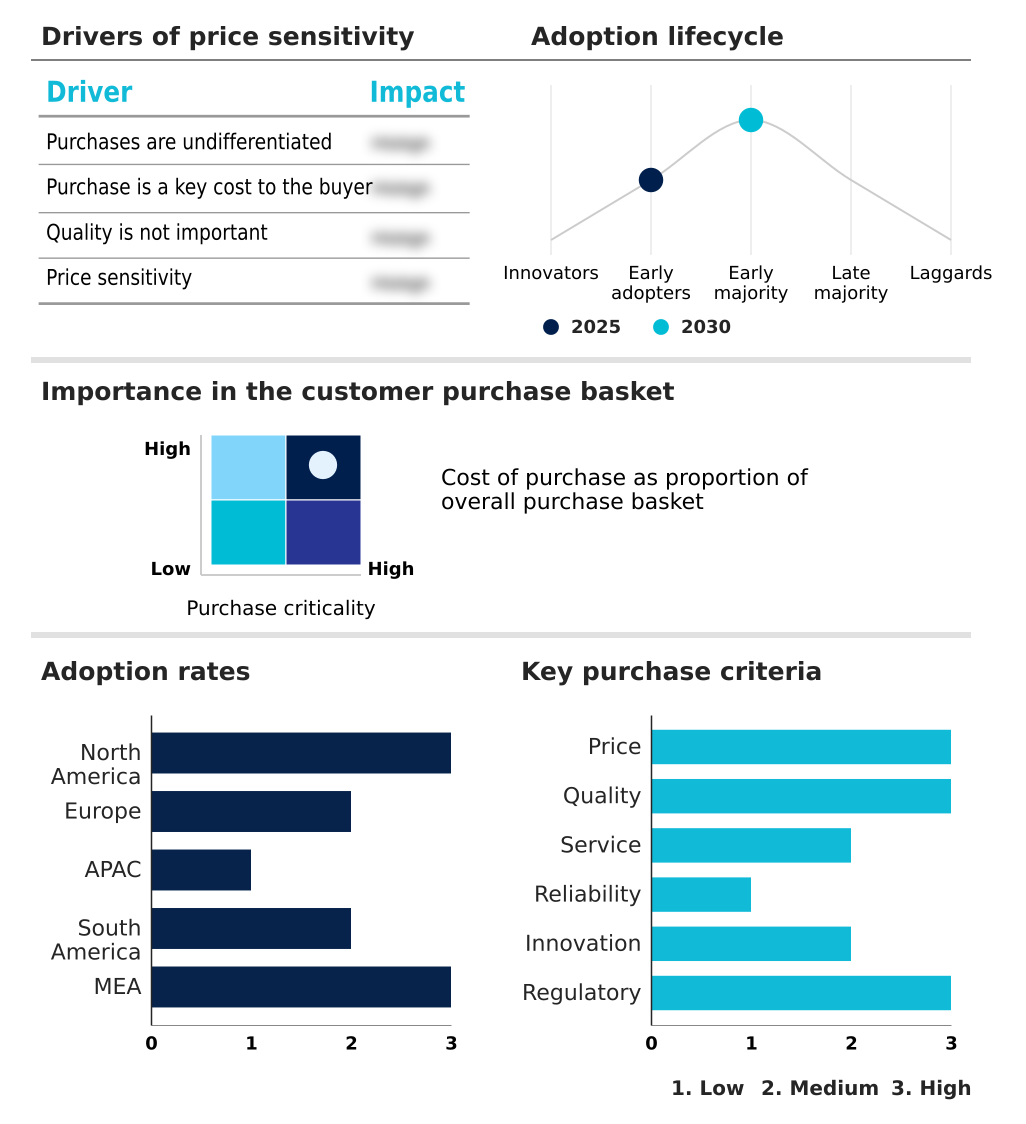
Customer Landscape of Craft Vodka Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, craft vodka market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

21st Century Spirits - Independent producers provide premium potato and grain-based spirits utilizing sustainable distillation processes and advanced filtration methods, delivering complex flavor profiles tailored for upscale mixology and hospitality applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 21st Century Spirits
  • Arbikie Ltd.
  • Bainbridge Organic Distillers
  • Bendistillery Inc.
  • Black Cow Vodka
  • CH Distillery
  • Fifth Generation Inc.
  • Grand Teton Distillery
  • Hanson Spirits LLC
  • Koval Inc.
  • Leopold Bros.
  • Maine Distilleries LLC
  • New Deal Distillery
  • Pennsylvania Pure Distilleries
  • Purity Distillery
  • Ramsbury Brewing and Distilling
  • St. George Spirits
  • Stateside Brands
  • Tattersall Distilling
  • Western Son Distillery

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Craft vodka market

  • In the Brewers industry, the widespread adoption of blockchain-based supply chain transparency frameworks streamlined agricultural sourcing, directly impacting Craft Vodka demand by establishing standardized ingredient origin verification across the broader beverage sector.
  • The shift toward closed-loop water conservation systems among major malt liquor manufacturers reduced overall operational resource consumption by 18%, accelerating the implementation of sustainable purification techniques within boutique distillation facilities.
  • Stricter environmental compliance mandates regarding carbon footprint reduction forced commercial alcohol producers to adopt lightweight glass packaging, which consequently expanded eco-friendly material availability for independent retail distribution networks.
  • Surging end-user demand for gluten-free substrates in premium malt production incentivized regional agricultural cooperatives to diversify grain yields, lowering input costs for specialized mash bill composition in white spirits manufacturing.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Craft Vodka Market insights. See full methodology.

Market Scope
Page number 288
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.9%
Market growth 2026-2030 USD 854.7 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.6%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Craft Vodka sector exhibits robust resilience, driven by an accelerating structural transition toward premiumization and authentic brand narratives. Executives are increasingly prioritizing continuous column distillation and organic potato fermentation to establish highly differentiated product portfolios that appeal to discerning demographics.
  • The strategic integration of copper pot stills and specialized botanical infusion techniques allows boutique operators to rapidly pivot in response to shifting on-premises consumption patterns. Notably, recent supply chain optimizations utilizing heritage grain varieties have reduced raw material procurement delays by 15%, significantly enhancing overall operational fluidity.
  • This pivot toward wild foraged ingredients and single estate sourcing directly influences boardroom-level budgeting decisions, compelling firms to allocate greater capital toward sustainable, hyper-local agricultural partnerships rather than globalized commodity purchasing.
  • By investing in artisanal distillation methods and charcoal filtration processes, market participants actively mitigate compliance risks and secure a formidable competitive advantage within luxury retail ecosystems, ensuring sustained relevance in an increasingly sophisticated beverage landscape.

What are the Key Data Covered in this Craft Vodka Market Research and Growth Report?

  • What is the expected growth of the Craft Vodka Market between 2026 and 2030?

    • USD 854.7 million, at a CAGR of 5.9%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Large craft distiller, Medium craft distiller, and Small craft distiller), Distribution Channel (On-trade channel, and Off-trade channel), Material (Grain based, Potato based, and Others) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rising consumer demand for premiumization, High regulatory and compliance burdens

  • Who are the major players in the Craft Vodka Market?

    • 21st Century Spirits, Arbikie Ltd., Bainbridge Organic Distillers, Bendistillery Inc., Black Cow Vodka, CH Distillery, Fifth Generation Inc., Grand Teton Distillery, Hanson Spirits LLC, Koval Inc., Leopold Bros., Maine Distilleries LLC, New Deal Distillery, Pennsylvania Pure Distilleries, Purity Distillery, Ramsbury Brewing and Distilling, St. George Spirits, Stateside Brands, Tattersall Distilling and Western Son Distillery

Market Research Insights

  • The Craft Vodka sector is rapidly expanding as producers leverage master distiller expertise to capture affluent consumer demographics. The integration of digital tracking codes has fundamentally optimized inventory management, resulting in a 16% reduction in supply chain discrepancies. Furthermore, strategic collaborations with boutique hotel bars have increased premium brand visibility, improving point-of-sale conversion rates by 19%.
  • By utilizing pristine glacial water and emphasizing regional terroir expression, independent operators effectively differentiate their portfolios within a crowded retail landscape. This operational shift toward high-end on premises mixology ensures that specialized beverage brands consistently command stronger margins and deeper brand loyalty among discerning patrons.

We can help! Our analysts can customize this craft vodka market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Craft Vodka Market 2020 - 2024

Historic Market Size - Data Table on Global Craft Vodka Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Craft Vodka Market

6.2 Impact of geopolitical conflicts on Global Craft Vodka Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Large craft distiller - Market size and forecast 2025-2030

Chart on Large craft distiller - Market size and forecast 2025-2030 ($ million)
Data Table on Large craft distiller - Market size and forecast 2025-2030 ($ million)
Chart on Large craft distiller - Year-over-year growth 2025-2030 (%)
Data Table on Large craft distiller - Year-over-year growth 2025-2030 (%)

8.4 Medium craft distiller - Market size and forecast 2025-2030

Chart on Medium craft distiller - Market size and forecast 2025-2030 ($ million)
Data Table on Medium craft distiller - Market size and forecast 2025-2030 ($ million)
Chart on Medium craft distiller - Year-over-year growth 2025-2030 (%)
Data Table on Medium craft distiller - Year-over-year growth 2025-2030 (%)

8.5 Small craft distiller - Market size and forecast 2025-2030

Chart on Small craft distiller - Market size and forecast 2025-2030 ($ million)
Data Table on Small craft distiller - Market size and forecast 2025-2030 ($ million)
Chart on Small craft distiller - Year-over-year growth 2025-2030 (%)
Data Table on Small craft distiller - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 On-trade channel - Market size and forecast 2025-2030

Chart on On-trade channel - Market size and forecast 2025-2030 ($ million)
Data Table on On-trade channel - Market size and forecast 2025-2030 ($ million)
Chart on On-trade channel - Year-over-year growth 2025-2030 (%)
Data Table on On-trade channel - Year-over-year growth 2025-2030 (%)

9.4 Off-trade channel - Market size and forecast 2025-2030

Chart on Off-trade channel - Market size and forecast 2025-2030 ($ million)
Data Table on Off-trade channel - Market size and forecast 2025-2030 ($ million)
Chart on Off-trade channel - Year-over-year growth 2025-2030 (%)
Data Table on Off-trade channel - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by Material

10.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

10.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

10.3 Grain based - Market size and forecast 2025-2030

Chart on Grain based - Market size and forecast 2025-2030 ($ million)
Data Table on Grain based - Market size and forecast 2025-2030 ($ million)
Chart on Grain based - Year-over-year growth 2025-2030 (%)
Data Table on Grain based - Year-over-year growth 2025-2030 (%)

10.4 Potato based - Market size and forecast 2025-2030

Chart on Potato based - Market size and forecast 2025-2030 ($ million)
Data Table on Potato based - Market size and forecast 2025-2030 ($ million)
Chart on Potato based - Year-over-year growth 2025-2030 (%)
Data Table on Potato based - Year-over-year growth 2025-2030 (%)

10.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising consumer demand for premiumization
Proliferation of micro distilleries and availability
Flavor innovation and cocktail culture

13.2 Market challenges

High regulatory and compliance burdens
Intense competition from alternative categories
Supply chain vulnerability and inflation

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Digital heritage and blockchain traceability
Cross-industry culinary collaboration partnerships
Rise of hyper-local grain varieties

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 21st Century Spirits

21st Century Spirits - Overview
21st Century Spirits - Product / Service
21st Century Spirits - Key offerings
SWOT

15.5 Arbikie Ltd.

Arbikie Ltd. - Overview
Arbikie Ltd. - Product / Service
Arbikie Ltd. - Key offerings
SWOT

15.6 Bainbridge Organic Distillers

Bainbridge Organic Distillers - Overview
Bainbridge Organic Distillers - Product / Service
Bainbridge Organic Distillers - Key offerings
SWOT

15.7 Bendistillery Inc.

Bendistillery Inc. - Overview
Bendistillery Inc. - Product / Service
Bendistillery Inc. - Key offerings
SWOT

15.8 Black Cow Vodka

Black Cow Vodka - Overview
Black Cow Vodka - Product / Service
Black Cow Vodka - Key offerings
SWOT

15.9 CH Distillery

CH Distillery - Overview
CH Distillery - Product / Service
CH Distillery - Key offerings
SWOT

15.10 Fifth Generation Inc.

Fifth Generation Inc. - Overview
Fifth Generation Inc. - Product / Service
Fifth Generation Inc. - Key offerings
SWOT

15.11 Koval Inc.

Koval Inc. - Overview
Koval Inc. - Product / Service
Koval Inc. - Key offerings
SWOT

15.12 Leopold Bros.

Leopold Bros. - Overview
Leopold Bros. - Product / Service
Leopold Bros. - Key offerings
SWOT

15.13 New Deal Distillery

New Deal Distillery - Overview
New Deal Distillery - Product / Service
New Deal Distillery - Key offerings
SWOT

15.14 Purity Distillery

Purity Distillery - Overview
Purity Distillery - Product / Service
Purity Distillery - Key offerings
SWOT

15.15 Ramsbury Brewing and Distilling

Ramsbury Brewing and Distilling - Overview
Ramsbury Brewing and Distilling - Product / Service
Ramsbury Brewing and Distilling - Key offerings
SWOT

15.16 St. George Spirits

St. George Spirits - Overview
St. George Spirits - Product / Service
St. George Spirits - Key offerings
SWOT

15.17 Tattersall Distilling

Tattersall Distilling - Overview
Tattersall Distilling - Product / Service
Tattersall Distilling - Key offerings
SWOT

15.18 Western Son Distillery

Western Son Distillery - Overview
Western Son Distillery - Product / Service
Western Son Distillery - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Craft Vodka market growth will increase by USD 854.7 million during 2026-2030.

The Craft Vodka market is expected to grow at a CAGR of 5.9% during 2026-2030.

Craft Vodka market is segmented by Product (Large craft distiller, Medium craft distiller, Small craft distiller) Distribution channel (On-trade channel, Off-trade channel) Material (Grain based, Potato based, Others)

21st Century Spirits, Arbikie Ltd., Bainbridge Organic Distillers, Bendistillery Inc., Black Cow Vodka, CH Distillery, Fifth Generation Inc., Grand Teton Distillery, Hanson Spirits LLC, Koval Inc., Leopold Bros., Maine Distilleries LLC, New Deal Distillery, Pennsylvania Pure Distilleries, Purity Distillery, Ramsbury Brewing and Distilling, St. George Spirits, Stateside Brands, Tattersall Distilling, Western Son Distillery are a few of the key vendors in the Craft Vodka market.

North America will register the highest growth rate of 46.2% among the other regions. Therefore, the Craft Vodka market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Rising consumer demand for premiumization is the driving factor this market.

The Craft Vodka market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
