Application Platform Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (UK, Germany, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Application Platform Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (UK, Germany, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 300 Pages SKU: IRTNTR40161

Market Overview at a Glance

$6.51 B
Market Opportunity
6.5%
CAGR 2025 - 2030
39.4%
North America Growth
$9.15 B
On-premises segment 2024

Application Platform Market Size 2026-2030

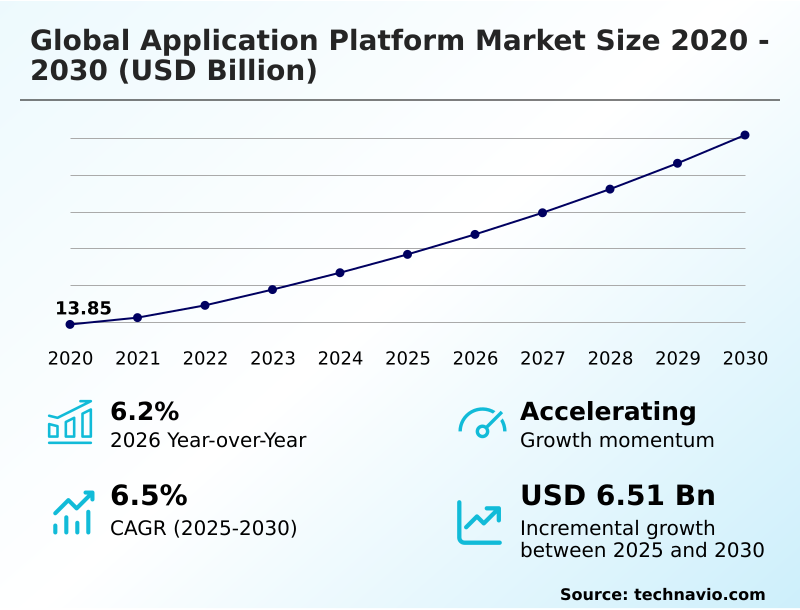
The application platform market size is valued to increase by USD 6.51 billion, at a CAGR of 6.5% from 2025 to 2030. Surging corporate demand for accelerated software delivery pipelines via internal developer platforms will drive the application platform market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.4% growth during the forecast period.
  • By Deployment - On-premises segment was valued at USD 9.15 billion in 2024
  • By End-user - Large enterprises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 10.32 billion
  • Market Future Opportunities: USD 6.51 billion
  • CAGR from 2025 to 2030 : 6.5%

Market Summary

  • The Application Platform sector exhibits rapid structural evolution driven by the critical corporate mandate to accelerate digital transformation. Modern enterprises systematically deploy integrated runtime environments and development frameworks to eliminate technical bottlenecks and streamline complex software delivery pipelines.
  • For instance, multinational retail conglomerates utilizing centralized platform environments have streamlined their supply chain application rollouts, effectively bypassing manual configuration delays to ensure continuous digital service availability. This operational shift yields measurable advantages, with organizations frequently observing a 45% reduction in initial software deployment timelines.
  • Surging corporate demand for internal developer platforms acts as a primary market driver, empowering engineering teams to automate infrastructure provisioning and maximize productivity. Conversely, the profound fragmentation of multi-cloud architectures creates a severe operational challenge, forcing IT departments to resolve persistent interoperability friction when connecting modern microservices with rigid legacy databases.
  • Overcoming these integration hurdles remains essential for enterprises seeking unified governance and seamless cross-border data management. Ultimately, continuous investments in hybrid-cloud scalability and intelligent automation ensure sustained commercial viability across diverse regulatory environments.

What will be the Size of the Application Platform Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Application Platform Market Segmented?

The application platform industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Deployment
    • On-premises
    • aPaaS
  • End-user
    • Large enterprises
    • SMEs
  • Component
    • Software
    • Services
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Deployment Insights

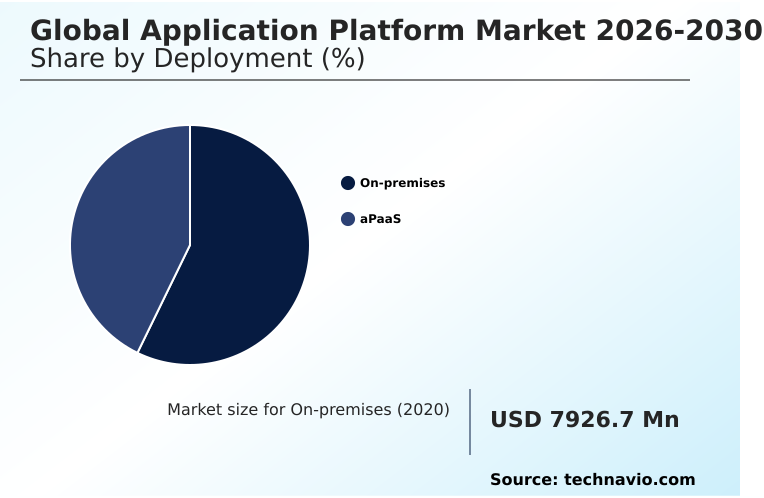
The on-premises segment is estimated to witness significant growth during the forecast period.

The on-premises segment of the Application Platform sector remains critical for enterprises requiring absolute data governance and isolated administrative control.

Highly regulated industries maintain mission-critical workloads within localized infrastructure to ensure strict regulatory compliance and network performance without public internet latencies.

Integrating modern microservices architecture and container orchestration into localized servers helps organizations achieve robust fault tolerance capabilities while enabling seamless legacy integration.

Upgraded systems feature automated provisioning and serverless computing frameworks, which significantly enhance developer velocity metrics and drive time to market acceleration. Consequently, these advancements yield a 15% improvement in operational efficiency by eliminating manual configuration delays.

Fusing cloud native development principles within air-gapped environments directly facilitates cognitive load reduction for busy internal engineering teams.
Get Free Sample

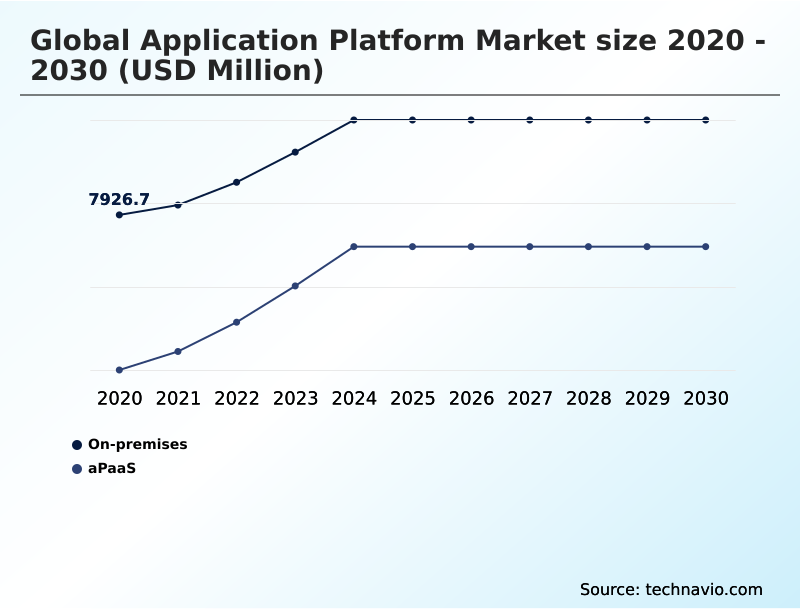
The On-premises segment was valued at USD 9.15 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
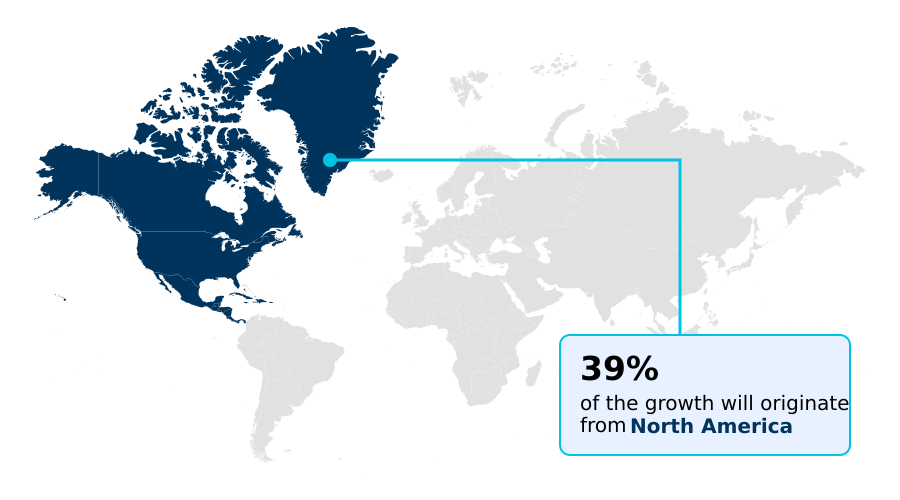
See How Application Platform Market Demand is Rising in North America Get Free Sample

The Application Platform demonstrates distinct evolutionary trajectories as businesses adapt strategies to resolve engineering bottlenecks.

North America leads the transition, where heavy reliance on hybrid cloud environments and generative ai coding assistants results in a 35% faster software deployment cycle compared to European counterparts.

While North American enterprises leverage autonomous workflow agents capable of autonomous task reasoning to handle real time data inputs effortlessly, Europe prioritizes strict compliance integrated within continuous integration pipelines.

European organizations record a 20% higher adoption rate of secure api lifecycle management tools to navigate rigid sovereign frameworks. Furthermore, businesses across regions utilize visual drag and drop modeling paired with natural language prompt interfaces to bypass traditional coding hurdles.

This democratization empowers users to apply custom logic extensions autonomously, effectively lowering external consulting costs by 28%. These regional variations highlight how distinct technical demands shape platform utilization and operational resilience.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous maturation of the Application Platform is fundamentally altering how organizations architect, scale, and maintain mission-critical digital systems. Modern commercial entities increasingly prioritize enterprise software deployment automation to eliminate the manual friction that historically delayed critical application rollouts.
  • By transitioning away from monolithic structures, organizations are aggressively implementing cloud native application modernization strategies that ensure greater fault tolerance and decoupled modularity across their IT ecosystems. As these hybrid architectures become standard, the necessity for robust multi cloud container management solutions grows exponentially, providing IT administrators with the visibility needed to orchestrate complex microservices without experiencing severe configuration drift.
  • In tandem with infrastructural enhancements, companies are exploring agentic ai embedded development environments to accelerate the creation of internal business logic. These intelligent frameworks allow systems to autonomously route supply chain data and resolve invoice discrepancies without requiring constant human oversight, effectively decreasing manual processing errors by nearly a third when compared to legacy manual data entry systems.
  • Furthermore, the rapid adoption of low code enterprise workflow generation empowers citizen developers across departments to construct functional applications rapidly. This democratization bridges persistent engineering talent gaps, aligning technical delivery closely with immediate operational demands. Through these multifaceted technological advancements, organizations achieve superior agility, optimize cloud infrastructure expenditures, and maintain robust competitive positioning in a demanding corporate landscape.
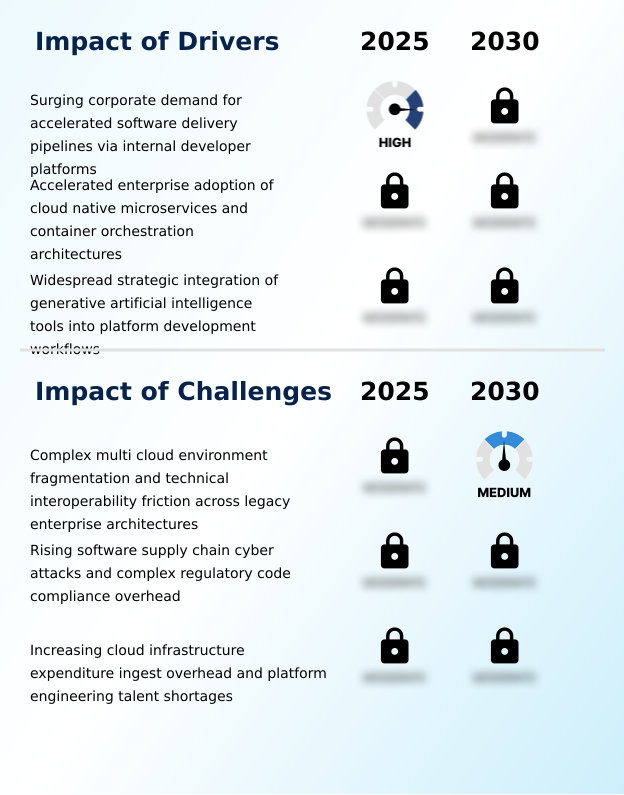
What are the key market drivers leading to the rise in the adoption of Application Platform Industry?

  • Surging corporate demand for accelerated software delivery pipelines through centralized internal developer platforms serves as the core catalyst propelling market expansion.

  • The escalating necessity for robust digital resilience acts as a primary catalyst expanding the Application Platform sector. Enterprises face unpredictable traffic surges, compelling them to implement intelligent workload auto scaling across distributed edge computing nodes.
  • This dynamic capacity management supports granular financial operations, effectively reducing excess infrastructure spending by 24%. Simultaneously, rising cyber threats force organizations to strengthen their supply chain cyber defense.
  • Companies integrate zero trust network access and strict role based access controls to secure corporate endpoints. Automated vulnerability scanning alongside continuous container registry scanning prevents malicious code injections, lowering critical security breaches by 38%.
  • Furthermore, international data sovereignty compliance mandates require continuous auditing, which IT teams automate through telemetry data processing. These structural drivers empower businesses to sustain secure software operations across global networks.

What are the market trends shaping the Application Platform Industry?

  • The widespread convergence of low-code development frameworks with robust enterprise application architectures defines the primary upcoming market trend.

  • The widespread architectural convergence of enterprise platforms is fundamentally accelerating software delivery capabilities. As organizations mandate higher system agility, they aggressively transition toward multi runtime composability to orchestrate decoupled core services independently across distributed networks. This structural shift establishes robust latency reduction strategies by utilizing dynamic load balancing to route traffic instantly during peak traffic spikes.
  • Consequently, companies achieve a 35% improvement in resource utilization optimization, significantly lowering their cloud hosting expenditures. IT departments are concurrently adopting advanced infrastructure as code to manage complex service mesh configurations securely. This automation guarantees effective configuration drift mitigation, decreasing system outages by 28%.
  • Furthermore, the incorporation of modular building blocks within accessible low code environments empowers both engineers and citizen developers to assemble functional applications collaboratively. By streamlining these deployment mechanisms, businesses effectively bypass traditional engineering bottlenecks and maintain continuous service availability.

What challenges does the Application Platform Industry face during its growth?

  • The fragmentation of complex multi-cloud environments and persistent technical interoperability friction across legacy enterprise architectures present significant hurdles impeding industry growth.

  • Multi-cloud environment fragmentation severely impedes continuous operational efficiency within the Application Platform space. Organizations struggle to maintain cross cloud portability when transitioning monolithic systems into modern event driven architecture. This friction inflates engineering overhead, creating a 32% increase in migration timelines. Adopting legacy modernization frameworks requires extensive technical debt management to prevent disruptions during transitions.
  • Furthermore, executing high-performance workloads like vector data processing demands specialized resources that lack predictable pricing structures, frequently causing budget overruns. Regulatory mandates also strain IT departments by requiring meticulous software bill of materials reporting to verify code integrity. Unifying these heterogeneous environments complicates routine maintenance, forcing administrators to delay crucial automated patch deployment protocols by 18%.
  • Resolving these structural hurdles remains critical for scaling enterprise software safely.

Exclusive Technavio Analysis on Customer Landscape

The application platform market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the application platform market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
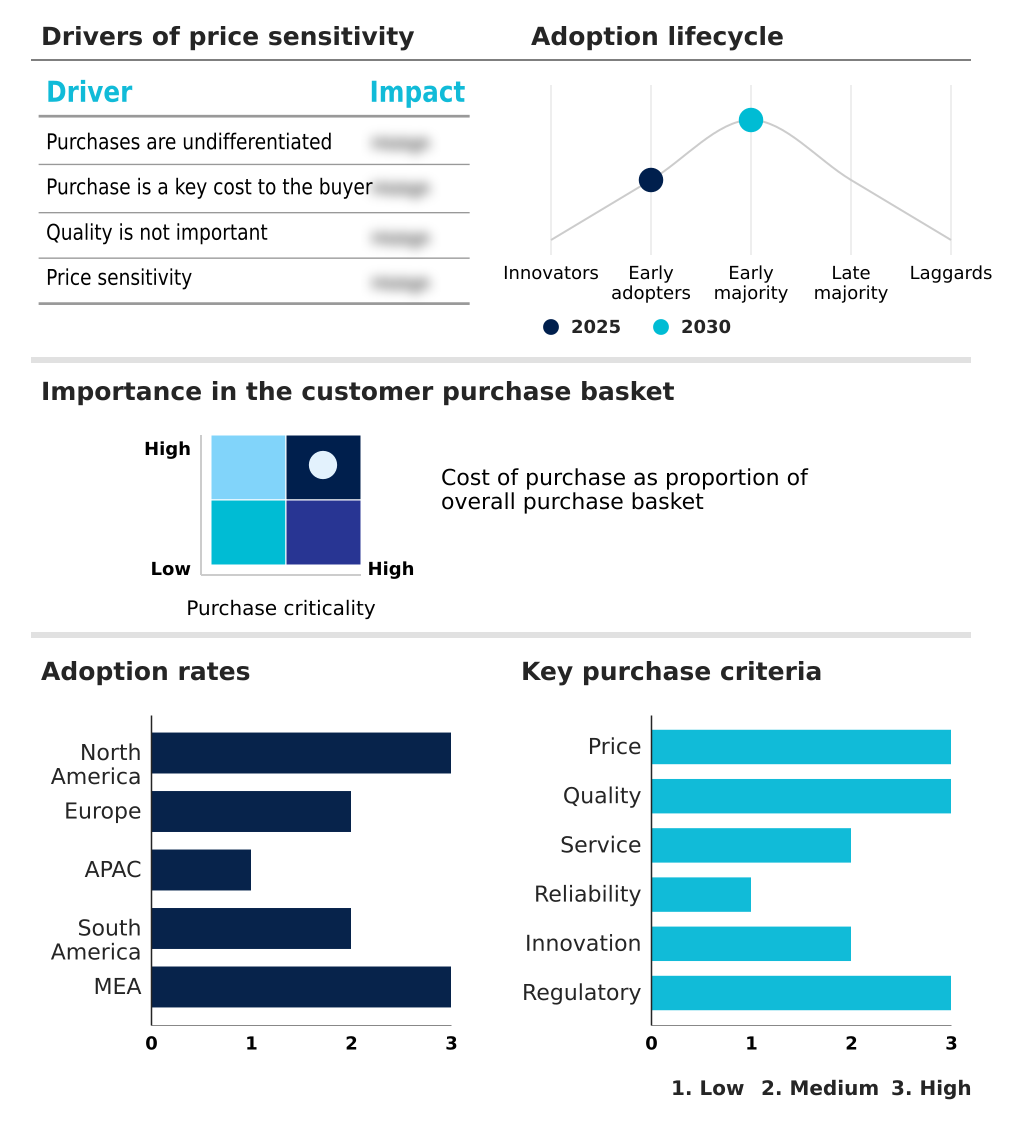
Customer Landscape of Application Platform Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, application platform market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Adobe Inc. - The portfolio features an integrated digital experience suite, commerce solutions, and content management architectures designed to optimize enterprise workflows and elevate cross-channel customer engagement continuously.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Adobe Inc.
  • Alibaba Cloud
  • Amazon.com Inc.
  • Appian Corp.
  • Broadcom Inc.
  • Google LLC
  • HCLSoftware
  • Huawei Technologies Co. Ltd.
  • IBM Corp.
  • Mendix Technology BV
  • Microsoft Corp.
  • Nintex Global Ltd.
  • Oracle Corp.
  • OutSystems Software Rede SA
  • Pegasystems Inc.
  • Progress Software Corp.
  • Salesforce Inc.
  • SAP SE
  • ServiceNow Inc.
  • Tencent Holdings Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Application platform market

  • In the Systems Software industry, the rapid standardization of distributed computing architectures has accelerated the adoption of modular building blocks, directly impacting Application Platform demand by increasing reliance on workload auto scaling and granular financial operations that reduce server maintenance overhead by 22%.
  • Stringent international data residency regulations have mandated robust internal governance frameworks, compelling organizations to implement strict role based access controls and automated patch deployment protocols that decrease compliance auditing times by 40% across Application Platform deployments.
  • The rising frequency of open-source vulnerabilities has forced enterprise software vendors to prioritize software bill of materials reporting, driving a 35% surge in Application Platform adoption designed specifically for container registry scanning and supply chain cyber defense.
  • Advancements in processing hardware have facilitated the execution of complex machine learning models directly at the network perimeter, boosting Application Platform utilization by enabling latency reduction strategies and resource utilization optimization that improve response speeds by 28%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Application Platform Market insights. See full methodology.

Market Scope
Page number 300
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 6.5%
Market growth 2026-2030 USD 6508.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.2%
Key countries US, Canada, Mexico, UK, Germany, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Application Platform sector is undergoing a profound structural shift as corporate leadership integrates advanced software orchestration directly into boardroom-level compliance and budgeting strategies. Executives recognize that rigid IT infrastructure stifles agility, prompting widespread adoption of legacy modernization frameworks designed to transition monolithic systems toward scalable event driven architecture.
  • This strategic pivot allows organizations to process vast user requests instantaneously while maintaining robust operational continuity. To mitigate rising cybersecurity risks and satisfy strict data sovereignty compliance, platforms now embed zero trust network access and automated vulnerability scanning natively into their runtime environments.
  • This proactive governance posture ensures that security checks do not impede developer velocity, resulting in a 35% reduction in compliance-related software deployment delays. Additionally, administrators utilize comprehensive telemetry data processing to monitor system health and optimize resource allocation dynamically. Securing cross cloud portability remains imperative for enterprises seeking to avoid vendor lock-in and negotiate favorable hosting contracts.
  • Ultimately, modernizing the application execution layer secures long-term digital competitiveness, enabling seamless feature delivery across highly regulated global industries.

What are the Key Data Covered in this Application Platform Market Research and Growth Report?

  • What is the expected growth of the Application Platform Market between 2026 and 2030?

    • USD 6.51 billion, at a CAGR of 6.5%

  • What segmentation does the market report cover?

    • The report is segmented by Deployment (On-premises, and aPaaS), End-user (Large enterprises, and SMEs), Component (Software, and Services) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Surging corporate demand for accelerated software delivery pipelines via internal developer platforms, Complex multi cloud environment fragmentation and technical interoperability friction across legacy enterprise architectures

  • Who are the major players in the Application Platform Market?

    • Adobe Inc., Alibaba Cloud, Amazon.com Inc., Appian Corp., Broadcom Inc., Google LLC, HCLSoftware, Huawei Technologies Co. Ltd., IBM Corp., Mendix Technology BV, Microsoft Corp., Nintex Global Ltd., Oracle Corp., OutSystems Software Rede SA, Pegasystems Inc., Progress Software Corp., Salesforce Inc., SAP SE, ServiceNow Inc. and Tencent Holdings Ltd.

Market Research Insights

  • The Application Platform sector provides critical digital infrastructure enabling modern enterprises to accelerate software delivery and maintain operational resilience. Organizations increasingly adopt these unified environments to implement latency reduction strategies and orchestrate decoupled core services across distributed networks. By prioritizing technical debt management, companies adopting advanced platforms achieve a 30% reduction in long-term maintenance expenditures.
  • Furthermore, the integration of automated governance protocols ensures effective configuration drift mitigation, decreasing system downtime instances by 22% annually. Corporate IT leaders also demand predictable pricing structures to control volatile cloud consumption budgets effectively. These measurable improvements in workflow automation and financial oversight highlight the indispensable role of modern application platforms in sustaining competitive business operations.

We can help! Our analysts can customize this application platform market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Component
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Application Platform Market 2020 - 2024

Historic Market Size - Data Table on Global Application Platform Market 2020 - 2024 ($ million)

5.2 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Component segment analysis 2020 - 2024

Historic Market Size - Component Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global application platform market

6.2 Impact of geopolitical conflicts on global application platform market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Deployment

8.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

8.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

8.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

8.4 aPaaS - Market size and forecast 2025-2030

Chart on aPaaS - Market size and forecast 2025-2030 ($ million)
Data Table on aPaaS - Market size and forecast 2025-2030 ($ million)
Chart on aPaaS - Year-over-year growth 2025-2030 (%)
Data Table on aPaaS - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Large enterprises - Market size and forecast 2025-2030

Chart on Large enterprises - Market size and forecast 2025-2030 ($ million)
Data Table on Large enterprises - Market size and forecast 2025-2030 ($ million)
Chart on Large enterprises - Year-over-year growth 2025-2030 (%)
Data Table on Large enterprises - Year-over-year growth 2025-2030 (%)

9.4 SMEs - Market size and forecast 2025-2030

Chart on SMEs - Market size and forecast 2025-2030 ($ million)
Data Table on SMEs - Market size and forecast 2025-2030 ($ million)
Chart on SMEs - Year-over-year growth 2025-2030 (%)
Data Table on SMEs - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Component

10.1 Market segments

Chart on Component - Market share 2025-2030 (%)
Data Table on Component - Market share 2025-2030 (%)

10.2 Comparison by Component

Chart on Comparison by Component
Data Table on Comparison by Component

10.3 Software - Market size and forecast 2025-2030

Chart on Software - Market size and forecast 2025-2030 ($ million)
Data Table on Software - Market size and forecast 2025-2030 ($ million)
Chart on Software - Year-over-year growth 2025-2030 (%)
Data Table on Software - Year-over-year growth 2025-2030 (%)

10.4 Services - Market size and forecast 2025-2030

Chart on Services - Market size and forecast 2025-2030 ($ million)
Data Table on Services - Market size and forecast 2025-2030 ($ million)
Chart on Services - Year-over-year growth 2025-2030 (%)
Data Table on Services - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Component

Market opportunity by Component ($ million)
Data Table on Market opportunity by Component ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging corporate demand for accelerated software delivery pipelines via internal developer platforms
Accelerated enterprise adoption of cloud native microservices and container orchestration architectures
Widespread strategic integration of generative artificial intelligence tools into platform development workflows

13.2 Market challenges

Complex multi cloud environment fragmentation and technical interoperability friction across legacy enterprise architectures
Rising software supply chain cyber attacks and complex regulatory code compliance overhead
Increasing cloud infrastructure expenditure ingest overhead and platform engineering talent shortages

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Widespread platform convergence of low code development and enterprise application architecture
Deployment of agentic AI assistants and autonomous workflows within platform runtime engines
Rapid shift toward multi runtime composability and serverless edge application platform infrastructures

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Adobe Inc.

Adobe Inc. - Overview
Adobe Inc. - Business segments
Adobe Inc. - Key news
Adobe Inc. - Key offerings
Adobe Inc. - Segment focus
SWOT

15.5 Alibaba Cloud

Alibaba Cloud - Overview
Alibaba Cloud - Product / Service
Alibaba Cloud - Key offerings
SWOT

15.6 Amazon.com Inc.

Amazon.com Inc. - Overview
Amazon.com Inc. - Business segments
Amazon.com Inc. - Key news
Amazon.com Inc. - Key offerings
Amazon.com Inc. - Segment focus
SWOT

15.7 Broadcom Inc.

Broadcom Inc. - Overview
Broadcom Inc. - Business segments
Broadcom Inc. - Key news
Broadcom Inc. - Key offerings
Broadcom Inc. - Segment focus
SWOT

15.8 Google LLC

Google LLC - Overview
Google LLC - Product / Service
Google LLC - Key news
Google LLC - Key offerings
SWOT

15.9 Huawei Technologies Co. Ltd.

Huawei Technologies Co. Ltd. - Overview
Huawei Technologies Co. Ltd. - Product / Service
Huawei Technologies Co. Ltd. - Key offerings
SWOT

15.10 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.11 Microsoft Corp.

Microsoft Corp. - Overview
Microsoft Corp. - Business segments
Microsoft Corp. - Key news
Microsoft Corp. - Key offerings
Microsoft Corp. - Segment focus
SWOT

15.12 Oracle Corp.

Oracle Corp. - Overview
Oracle Corp. - Business segments
Oracle Corp. - Key news
Oracle Corp. - Key offerings
Oracle Corp. - Segment focus
SWOT

15.13 Pegasystems Inc.

Pegasystems Inc. - Overview
Pegasystems Inc. - Business segments
Pegasystems Inc. - Key offerings
Pegasystems Inc. - Segment focus
SWOT

15.14 Progress Software Corp.

Progress Software Corp. - Overview
Progress Software Corp. - Product / Service
Progress Software Corp. - Key offerings
SWOT

15.15 Salesforce Inc.

Salesforce Inc. - Overview
Salesforce Inc. - Business segments
Salesforce Inc. - Key news
Salesforce Inc. - Key offerings
Salesforce Inc. - Segment focus
SWOT

15.16 SAP SE

SAP SE - Overview
SAP SE - Business segments
SAP SE - Key news
SAP SE - Key offerings
SAP SE - Segment focus
SWOT

15.17 ServiceNow Inc.

ServiceNow Inc. - Overview
ServiceNow Inc. - Product / Service
ServiceNow Inc. - Key news
ServiceNow Inc. - Key offerings
SWOT

15.18 Tencent Holdings Ltd.

Tencent Holdings Ltd. - Overview
Tencent Holdings Ltd. - Business segments
Tencent Holdings Ltd. - Key offerings
Tencent Holdings Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Application Platform market growth will increase by USD 6508.3 million during 2026-2030.

The Application Platform market is expected to grow at a CAGR of 6.5% during 2026-2030.

Application Platform market is segmented by Deployment (On-premises, aPaaS) End-user (Large enterprises, SMEs) Component (Software, Services)

Adobe Inc., Alibaba Cloud, Amazon.com Inc., Appian Corp., Broadcom Inc., Google LLC, HCLSoftware, Huawei Technologies Co. Ltd., IBM Corp., Mendix Technology BV, Microsoft Corp., Nintex Global Ltd., Oracle Corp., OutSystems Software Rede SA, Pegasystems Inc., Progress Software Corp., Salesforce Inc., SAP SE, ServiceNow Inc., Tencent Holdings Ltd. are a few of the key vendors in the Application Platform market.

North America will register the highest growth rate of 39.4% among the other regions. Therefore, the Application Platform market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, UK, Germany, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Surging corporate demand for accelerated software delivery pipelines via internal developer platforms is the driving factor this market.

The Application Platform market vendors should focus on grabbing business opportunities from the Deployment segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
